


When High-Net-Worth Palm Beach Residents May Need Life Insurance
Life insurance for high-net-worth individuals in Palm Beach can remain useful after children grow up. Coverage may support a surviving spouse, provide funds for beneficiaries, or help carry out family legacy plans. Whether it still fits depends on the financial responsibilities and goals that remain.
It makes sense to reassess protection as family needs change. Grown children may be financially independent, while estate plans, charitable intentions, or a spouse’s future security still shape the decision. The right life insurance for high-net-worth individuals in Palm Beach starts with those priorities, not simply the fact that children have reached adulthood.
This article explains when coverage may remain useful, how beneficiary payments work, and which options to consider in Palm Beach County. You’ll learn how term, whole life, and universal life differ, helping you weigh which direction may fit your family’s goals.
Life Insurance in Palm Beach Gardens: Why Do I Need It?
Life insurance can provide cash value access during life and funds for beneficiaries after death. Reviewing a policy can help reveal whether existing coverage still fits your estate goals.
Living Benefits Through Policy Access
Whole life cash value is guaranteed and may be borrowed against. Some policies also allow withdrawals, giving policyholders ways to access value while living. Before considering access, review the policy’s terms, current cash value, premiums, and any outstanding loans. The death benefit is generally the face amount less policy indebtedness, provided premiums are paid.
For an existing policy, review coverage, beneficiaries, and compensation disclosures before deciding to replace it. A 1035 exchange may preserve an annuity’s tax-deferred status without ordinary-income treatment on its gain when its surrender schedule has cleared and expenses are uncompetitive. For a lost policy, the National Association of Insurance Commissioners’ Life Insurance Policy Locator Service can help Florida residents search.
Underwriting reviews medical history and risk classification; an applicant may need a medical exam. Large coverage requests also make it sensible to discuss how the requested amount relates to financial needs. Florida policies must become incontestable after being in force during the insured’s lifetime for 2 years, subject to exceptions, according to the Florida Legislature.
Coverage and Estate Liquidity Planning
There is no single coverage amount for affluent families. Estimate the funds beneficiaries may need, outstanding obligations, estate plans, and intended charitable gifts, then weigh those against available assets and existing policies. Federal estate tax follows federal rules, and the relevant exemption affects whether an estate owes tax. The applicable threshold and the estate’s circumstances shape the calculation.
A death benefit can provide beneficiaries with liquidity to address expenses or taxes without relying only on selling assets. An irrevocable life insurance trust, or ILIT, owns a policy through its trustee; the trust document governs control and how proceeds are distributed. Private placement life insurance can carry investment, liquidity, and tax risks, so its structure and policy terms matter. For Palm Beach families, a suitable advisor evaluates coverage alongside estate goals and policy ownership.
Beneficiary payments and claim timing
Most life insurance claims are paid within 10 days after the insurer receives a valid death certificate from the beneficiary. This is a general timing expectation, not a reason to delay notifying the insurer. A prompt claim submission helps begin the review and gives beneficiaries a clear next step during a difficult period.
In Florida, insurers must start paying interest on an unsettled claim the day after receiving proof of death. Beneficiaries can notify the insurer, submit proof of death, and follow its claim process. The insurer reviews the policy and beneficiary records before payment. Keeping those records current can help prevent avoidable questions about who should receive the death benefit.
How proceeds are divided depends partly on the beneficiary designation. A per capita designation divides proceeds among named beneficiaries, redistributing a deceased beneficiary’s share among the surviving beneficiaries. A per stirpes designation may direct a deceased beneficiary’s share to that person’s descendants. The choices lead to different outcomes if a named beneficiary dies before the policyholder.
For families with substantial wealth, beneficiary designations can affect how financial support reaches the next generation. Beneficiaries may use payments for living expenses, property costs, or other priorities. Life insurance proceeds generally aren’t subject to federal income tax in most instances. The policy’s terms and beneficiary records remain central to a claim, whether coverage is term or whole life insurance.
Reviewing beneficiary instructions as family circumstances change can help keep the intended distribution clear. Explore beneficiary planning support as part of a broader review of your life insurance protection.
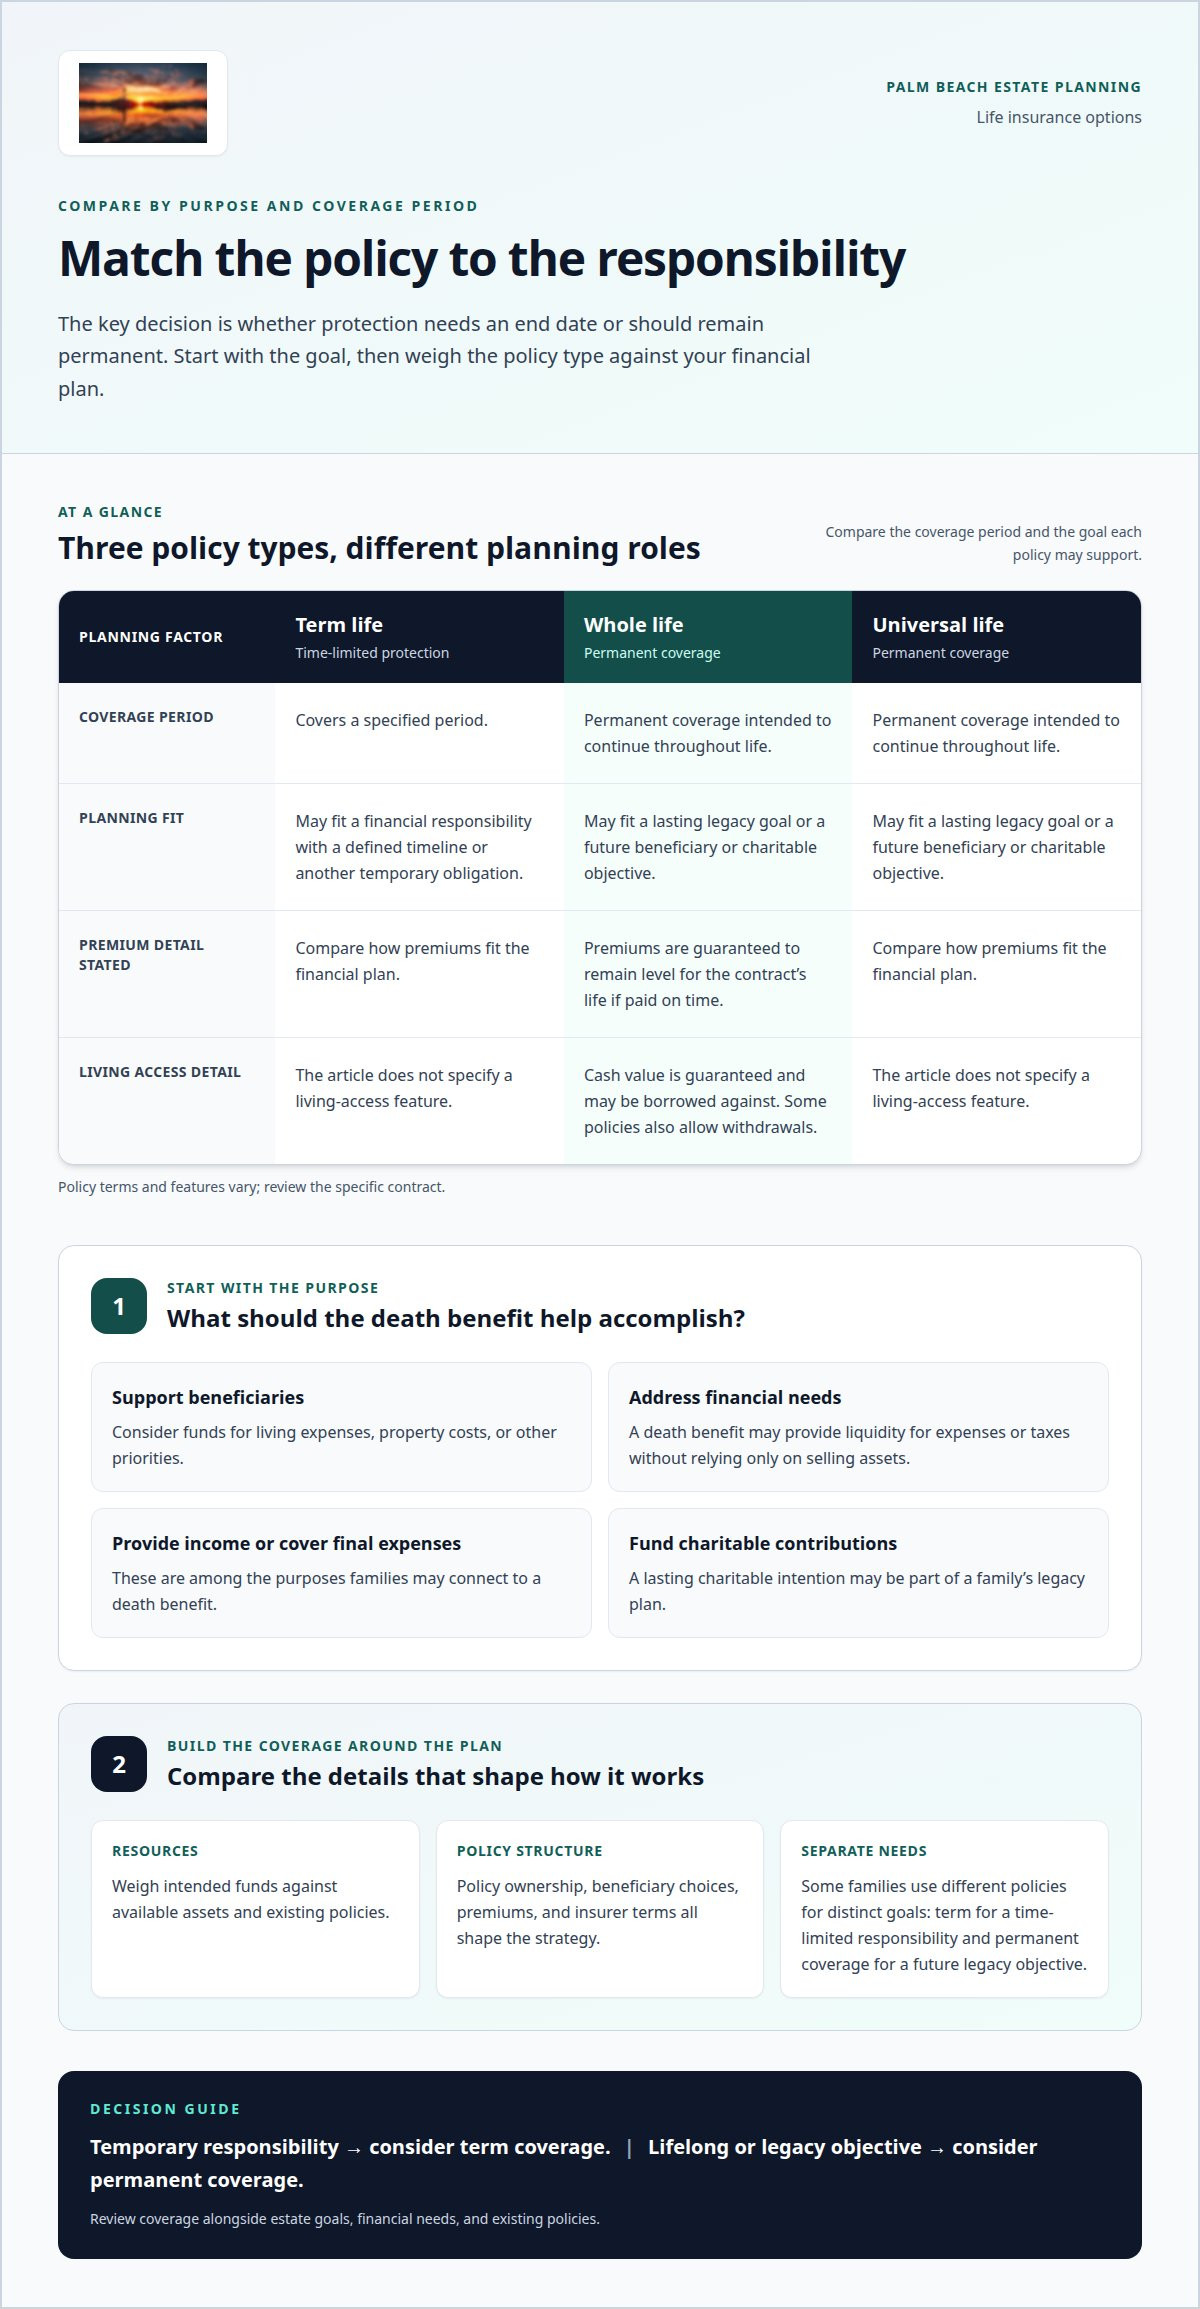
Life insurance options in Palm Beach Gardens
Florida families can match policy type and coverage period to their estate goals. The key decision is whether protection needs an end date or should remain permanent. When considering life insurance for high-net-worth individuals in Palm Beach, start with the purpose of coverage, then select a policy type that supports it.
Comparing Policy Types for Estate Planning
Term life insurance covers a specified period, making it useful when a financial responsibility has a defined timeline. Whole life and universal life provide permanent coverage, which may suit goals intended to continue throughout someone’s life. Whole life premiums are guaranteed to remain level for the contract’s life if paid on time.
For estate planning, compare how long protection is needed, how premiums fit the financial plan, and whether permanent coverage supports future beneficiary or charitable goals. A family seeking coverage for a temporary obligation may consider term, while a lasting legacy goal may point toward permanent insurance.
High-Net-Worth Insurance Strategies
High-net-worth strategies connect the death benefit to a clear purpose, such as supporting beneficiaries, addressing final expenses, providing income, or funding charitable contributions. Families can consider existing assets and policies, then assess whether term or permanent coverage fits each goal. This is a practical starting point for Palm Beach residents evaluating life insurance for high-net-worth individuals.
Some families use different policies for distinct needs rather than relying on one contract. Term coverage can address a time-limited responsibility, while whole life or universal life may support a future legacy objective. Policy ownership, beneficiary choices, premiums, and the insurer’s terms all shape how the strategy works.
An independent review can help clarify which benefits matter and how coverage fits an estate plan. Explore life insurance options for your estate goals and identify a suitable next step.
Safe Harbor Financial Resources
Safe Harbor Financial Resources helps Palm Beach families consider how life insurance fits changing responsibilities, estate goals, and plans to support beneficiaries. A free consultation can clarify whether coverage remains useful after children grow up and how existing policies align with future priorities. The discussion can also help distinguish temporary needs from goals that may call for long-term protection.
Options include term life insurance, whole life insurance, and life insurance with living benefits. Each serves different needs, so the right discussion begins with the purpose and duration of coverage and how it fits the broader financial picture. Clear, patient guidance can make a complex decision easier to approach.
Contact Safe Harbor Financial Resources to discuss your life insurance needs.
Set a Clear Course for Your Family’s Next Chapter
Family priorities can shift as children become independent, assets change, or plans for the future take shape. Use those milestones to revisit what protection should accomplish, who it should benefit, and how it fits alongside other financial decisions. A thoughtful review can help keep your choices aligned with the life your family is building.
For life insurance for high-net-worth individuals in Palm Beach, Safe Harbor Financial Resources offers guidance on options including term life insurance and life insurance with living benefits. The agency also offers Medicare Supplement Insurance (Medigap) for clients with distinct coverage needs.
Start a conversation with Safe Harbor Financial Resources about the protection that fits your next chapter. A steady, informed next step can help your family move forward with greater clarity.
Frequently Asked Questions
Is whole life insurance a good investment?
Whole life insurance is primarily insurance protection, so whether it fits as part of a financial plan depends on your goals. Consider how premiums compare with your budget, which policy values are guaranteed, and how access to cash value works under the contract. A family seeking lasting coverage may weigh these features differently from someone focused mainly on growth or liquidity.
What questions should affluent clients ask when comparing life insurance advisors and policies?
Ask how the advisor is compensated, which policy values are guaranteed, and what assumptions shape any illustrations. Also ask how a proposed policy fits your estate goals, what happens if premiums change or stop, and what replacing existing coverage could mean. In Palm Beach Gardens, make sure the discussion addresses your family’s priorities, not only the size of the death benefit.
What medical and financial underwriting requirements apply to large life insurance policies?
Underwriting reviews medical history and risk classification, and an applicant may need a medical exam. For large coverage requests, discuss how the requested amount relates to financial needs.
How do Florida insurance laws and creditor protections affect life insurance?
Florida policies must become incontestable after being in force during the insured’s lifetime for two years, subject to exceptions. Insurers must start paying interest on an unsettled claim the day after receiving proof of death. Creditor protections are not addressed.
Which Palm Beach life insurance advisors specialize in high-net-worth clients?
Safe Harbor Financial Resources helps Palm Beach families assess life insurance in light of changing responsibilities, estate goals, and support for beneficiaries.
Comments