


Retirement Annuity Calculator Florida: Estimate Your Income
The same savings balance can produce very different retirement income estimates. A retirement annuity calculator in Florida typically uses the amount invested, when payments begin, your age, the annuity’s rate or returns, and the payout option you select. The result is an estimate, not a full picture of how an annuity may fit your retirement plan.
It’s reasonable to want a clear monthly income figure before making a long-term decision. Understanding what goes into the calculation can help you interpret the estimate with greater confidence. This guide explains how savings, timing, annuity type, and payment choices shape potential income, introduces tools for different planning needs, and clarifies what a calculator can’t tell you about contract terms or your personal financial situation.
What Factors Affect Annuity Payout Calculations?
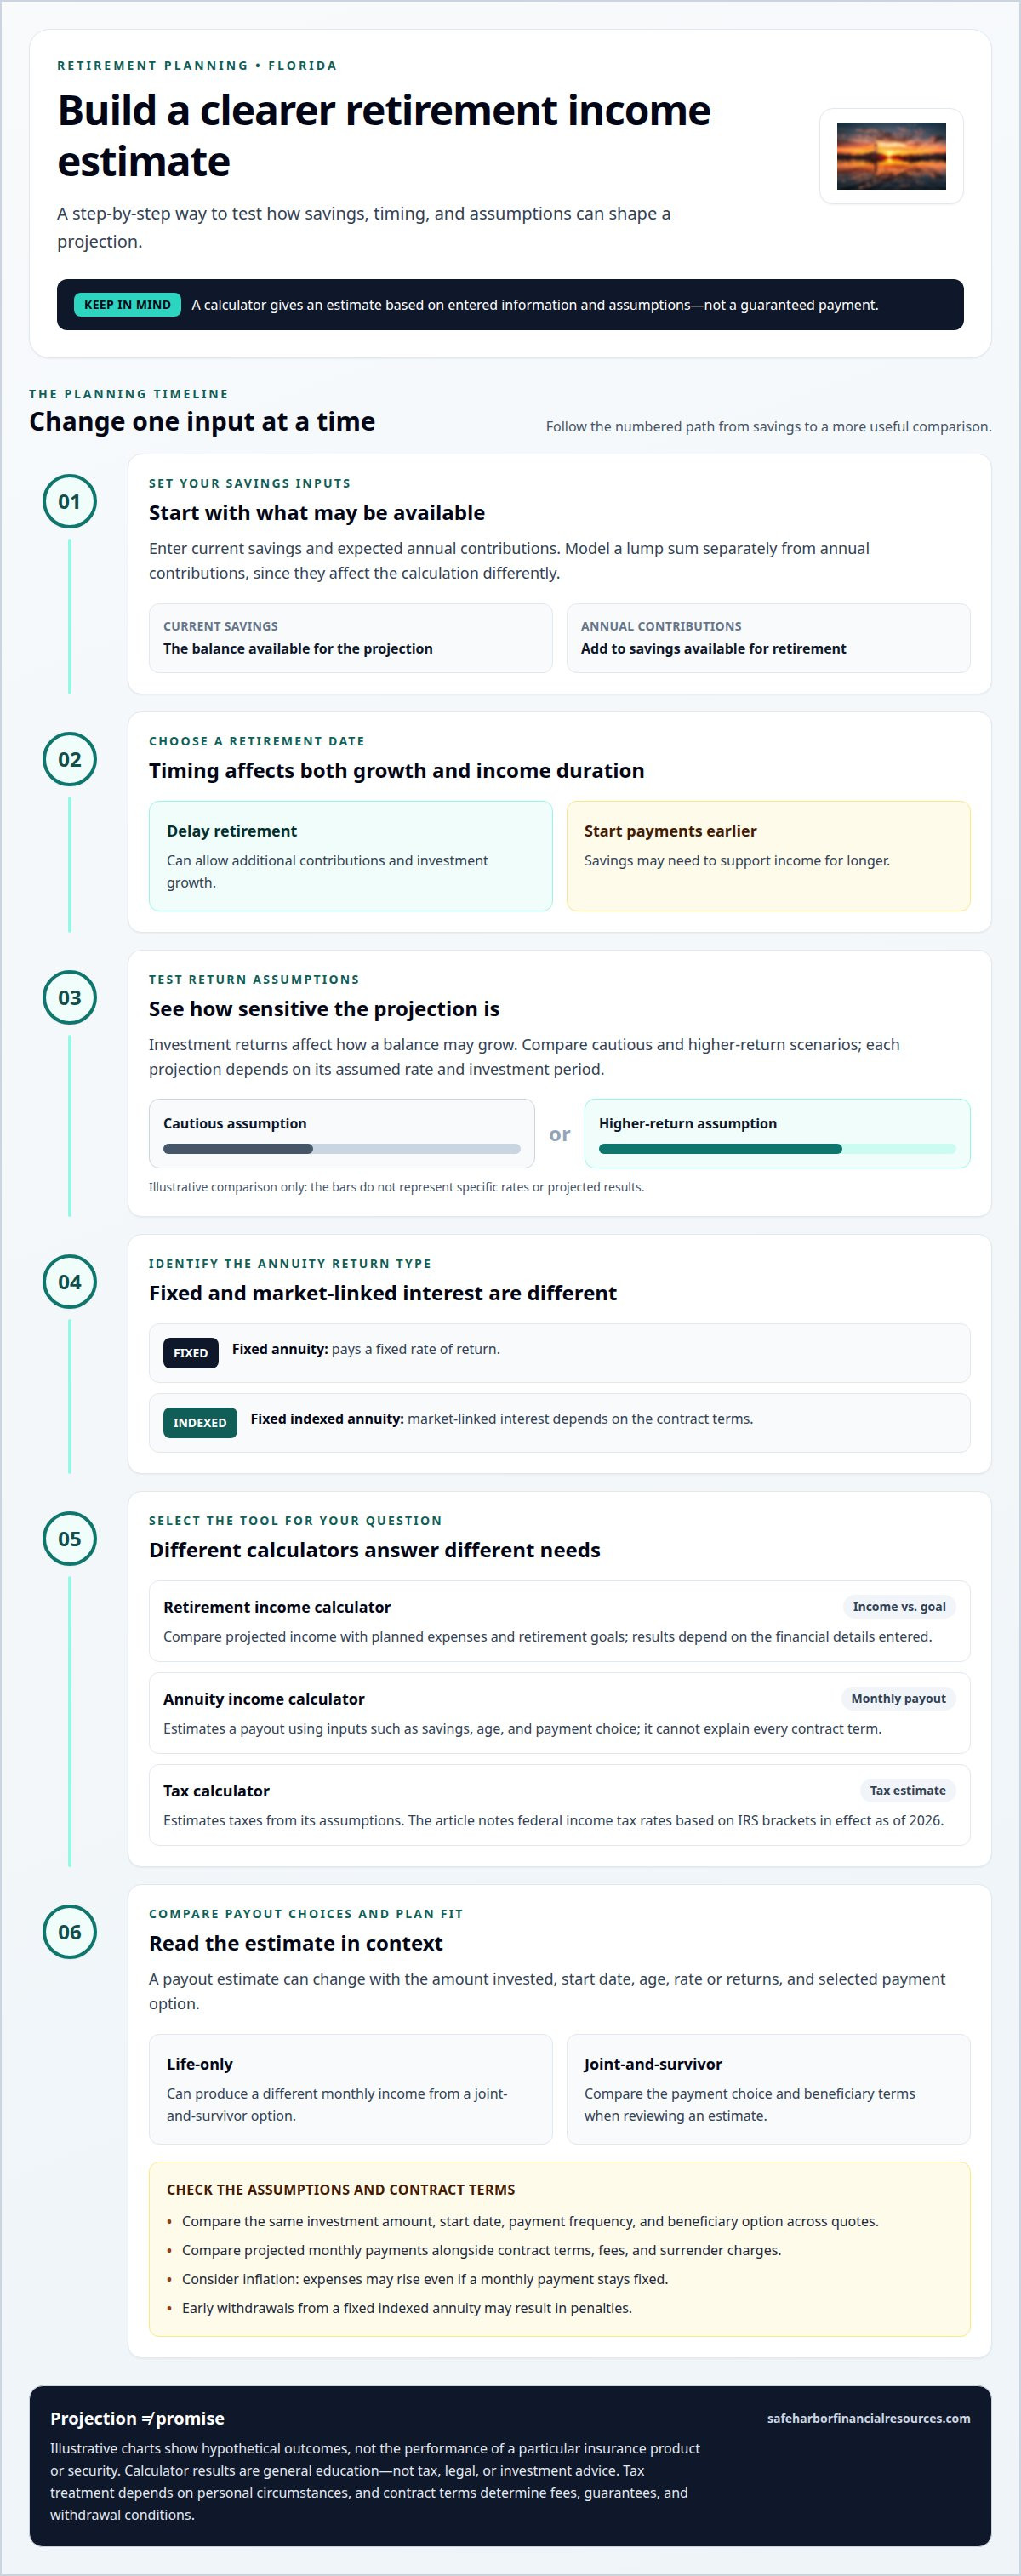
Your estimated monthly payment changes with the amount invested, start date, age, interest or investment returns, and payout option. A fixed annuity pays a fixed rate of return, while variable annuity payments can change with investment returns and may fall. These differences affect how savings translate into retirement income.
For savings-based planning, a retirement income calculator estimates how current savings and expected income sources may support your goals. Adjust the savings amount, retirement date, and assumptions to compare results. Include inflation in your planning, since expenses may rise even if a monthly payment stays fixed.
Lifetime income: An immediate annuity calculator estimates payments from a lump sum, age, and payout choice. A life-only option and a joint-and-survivor option can produce different monthly income.
Fixed income: A fixed annuity calculator helps estimate payments using its rate and contract terms. Payment timing and selected guarantees also affect the result.
Florida pension: A Florida pension calculator compares a monthly state pension payout with rolling a pension lump sum into an IRA fixed index annuity. Pension terms for a beneficiary depend on the plan.
Income needs: A retirement income calculator helps compare expected monthly income with planned expenses and retirement goals.
To compare annuity quotes from Florida insurers, use the same investment amount, start date, payment frequency, and beneficiary option for each estimate. Then compare projected monthly payments and contract terms side by side.
Annuity tax treatment depends on personal circumstances; the calculator is educational, not tax advice. Its federal income tax rates use IRS brackets in effect as of 2026, according to the Internal Revenue Service.
Fees and surrender charges depend on contract terms. Early withdrawals from a fixed indexed annuity may result in penalties, so consider withdrawal terms when comparing estimates.
Calculator limitations and disclaimers
An annuity calculator estimates income using the information and assumptions entered; it does not guarantee a monthly payment. Changing the lump sum, start date, interest assumptions, or payment option can change the result. Illustrative charts show hypothetical outcomes, not the performance of a particular insurance product or security.
Use each tool for a specific purpose, and read its assumptions:
Annuity income calculator: Estimates a monthly payout from inputs such as savings, age, and payment choice. It can’t explain every contract term.
Retirement income calculator: Helps compare projected income with a retirement goal. Its result depends on the financial details entered.
Tax calculator: Estimates taxes from its assumptions. According to the Internal Revenue Service, this calculator bases federal income tax rates on IRS tax brackets in effect as of 2026.
These tools provide general education, not tax, legal, or investment advice. A deferred annuity’s future income depends on its contract terms and assumptions about interest or growth. A financial advisor can help interpret those details; consult a tax and legal advisor about your individual situation.
Are annuities protected by the Florida Life and Health Insurance Guaranty Association? A calculator can’t determine whether a specific annuity contract receives that protection. The answer depends on applicable Florida rules and the contract, not on an estimated monthly payout.
For a more grounded estimate, compare the calculator’s assumptions with the terms of the fixed annuity or fixed indexed annuity you’re considering. Explore fixed annuity guidance from Safe Harbor Financial Resources as you evaluate how an insurance contract may fit your income plan.
Results depend on the information provided and the assumptions used. Adjust your answers to reflect your financial situation, while keeping in mind that estimates can change.
Effects of annual savings, investment returns, and retirement age
A retirement projection changes when you adjust annual savings, investment returns, or the age you plan to stop working. Use a retirement annuity calculator Florida residents can use to test different assumptions, then compare the projected balance and potential payout. Change one input at a time to see its effect rather than treating one result as certain.
Annual contributions add to the savings available for retirement. Investment returns affect how that balance may grow, but the projection depends on the assumed rate and investment period. Compare cautious and higher-return scenarios to see how sensitive your plan is. A calculator’s projection reflects an assumption, not a minimum or guaranteed outcome.
Retirement age affects both the time available for growth and how long your savings must support you. Delaying retirement can allow additional contributions and investment growth; starting payments earlier can mean income needs to last longer. A retirement annuity calculator Florida users rely on can help test different retirement dates, while a monthly income calculator estimates how the revised balance could support payments.
For annuities, distinguish fixed returns from market-linked interest. A fixed annuity pays a fixed rate of return; a fixed indexed annuity’s market-linked interest depends on its terms. A purchase decision also involves how much security and access you want from your savings. Model a lump sum separately from annual contributions, since they affect the calculation differently.
Use a retirement income calculator to compare projected payments with expenses, then revisit the inputs as your savings or retirement date changes. For help reviewing how a fixed annuity may fit your retirement plan, discuss your retirement income assumptions.
Safe Harbor Financial Resources
Safe Harbor Financial Resources can help Palm Beach Gardens residents consider how insurance relates to their needs and priorities. A calculator offers a starting point; your savings, expected income, and goals give the estimate personal context. This perspective can be useful when weighing retirement choices or reviewing how insurance may support your plans.
The agency offers Whole Life Insurance, Term Life Insurance, and Life Insurance with Living Benefits. These products address different needs from an annuity estimate, so the right conversation depends on the question you’re trying to answer. Considering your goals and coverage needs together can make the next step clearer without treating a calculator result as a complete plan.
Contact Safe Harbor Financial Resources to discuss your retirement planning questions.
Turn your estimate into a clearer next step
A retirement annuity calculator in Florida can help you explore possibilities, but the next step is deciding what role predictable income should play in your broader retirement picture. Consider how your income plans relate to protection needs and healthcare costs. That broader perspective can help you make purposeful choices instead of focusing on a single projected monthly amount.
Safe Harbor Financial Resources offers Medicare Supplement Insurance (Medigap), Life Insurance with Living Benefits, and Term Life Insurance. These options address different needs, so a conversation can focus on the questions that matter to your circumstances and priorities.
Contact Safe Harbor Financial Resources to discuss your retirement planning questions and take a thoughtful next step.
Frequently Asked Questions
What Should You Know About Annuities?
An annuity is an insurance product that can provide income in exchange for a lump-sum payment. It’s a long-term contract used in retirement planning, so consider when payments begin and whether income is designed to last for life or a set period. These choices help determine how an annuity may fit alongside other retirement income sources.
The estimate depends on interest rates and the payout option, so it isn’t a universal quote. For a useful comparison, keep the age and purchase amount consistent, then compare payment options and start dates.
How long will my retirement savings last?
Your savings may last longer or shorter depending on withdrawals, investment performance, inflation, and other income. A retirement calculator can help model different spending patterns, such as steady withdrawals or higher costs early in retirement. Compare scenarios using your expected income and expenses, then revisit the estimates as your plans change.
What Kinds of Annuities Are There?
Common categories include fixed, fixed indexed, variable, immediate, and deferred annuities. Fixed annuities pay a fixed rate of return; variable payments can change with investment returns and may fall. Immediate annuities begin income after a lump-sum purchase, while deferred annuities start payments on a future date. Contract terms shape each option.
Why consider an income annuity?
An income annuity can provide retirement income for life or for a set period. It may suit someone who wants a defined stream of payments alongside other income sources. Compare the desired payment period and payout choice with your household’s needs. Its value lies in a payment structure designed around an income timeline, not a general savings estimate.
Comments