


What to Do When You’re About to Turn 65: A 2026 Checklist
If you’re wondering what to do when you're about to turn 65, start with two things: your Medicare enrollment dates and the health coverage you have now. Medicare has several coverage paths, and the right details to compare depend on your doctors, prescriptions, and budget priorities. You don’t have to sort it all out at once.
This 2026 checklist helps you identify the dates to review and the decisions to make before your birthday. Your Initial Enrollment Period lasts seven months, starting three months before your birthday month. When you enroll can affect when your coverage begins, so give yourself time to compare options.
You’ll review the enrollment timeline, compare Original Medicare with Medicare Advantage and Medigap, and see what to consider for prescription coverage. Gathering a few details in advance can make your Medicare decisions more manageable.
What to do before turning 65: build your Medicare timeline
Turning 65 doesn’t mean you need to make every insurance decision at once. A timeline gives you room to understand your options and avoid leaving enrollment until the last minute. Knowing what to do when you're about to turn 65 starts with your birthday month and the coverage you have now.
Which Medicare dates and personal details should you check first?
Your Initial Enrollment Period (IEP) generally lasts seven months: it starts three months before the month you turn 65, includes your birthday month, and ends three months afterward. Enrolling during the three months before your birthday month can help your coverage begin on time. If your birthday falls on the first day of a month, Medicare timing may shift. Verify your specific dates and coverage start date at Medicare.gov or through CMS.
Usually, your Initial Enrollment Period runs from three months before your 65th-birthday month through three months after it.
Mark your dates: Write down your birthday month and IEP window. Check Medicare.gov or CMS for your exact dates, especially if you were born on the first day of a month.
Review current coverage: Note whether your health insurance is connected to your own or a spouse’s current employment. This may affect your next steps, so don’t assume existing coverage automatically replaces Medicare enrollment.
Check Social Security notices: Automatic enrollment depends on your circumstances. People already receiving Social Security or Railroad Retirement Board benefits at least four months before turning 65 will likely be enrolled automatically in Parts A and B. Read any notices you receive and confirm which parts and effective dates they show.
For guidance from Safe Harbor Financial Resources, you can also consult professional advisors to help map out your transition. For a broad introduction to Medicare’s parts and administration, see the Medicare (United States) Wikipedia article. Use Medicare.gov or CMS to verify your personal enrollment dates and next steps.
Compare Medicare coverage choices before you enroll
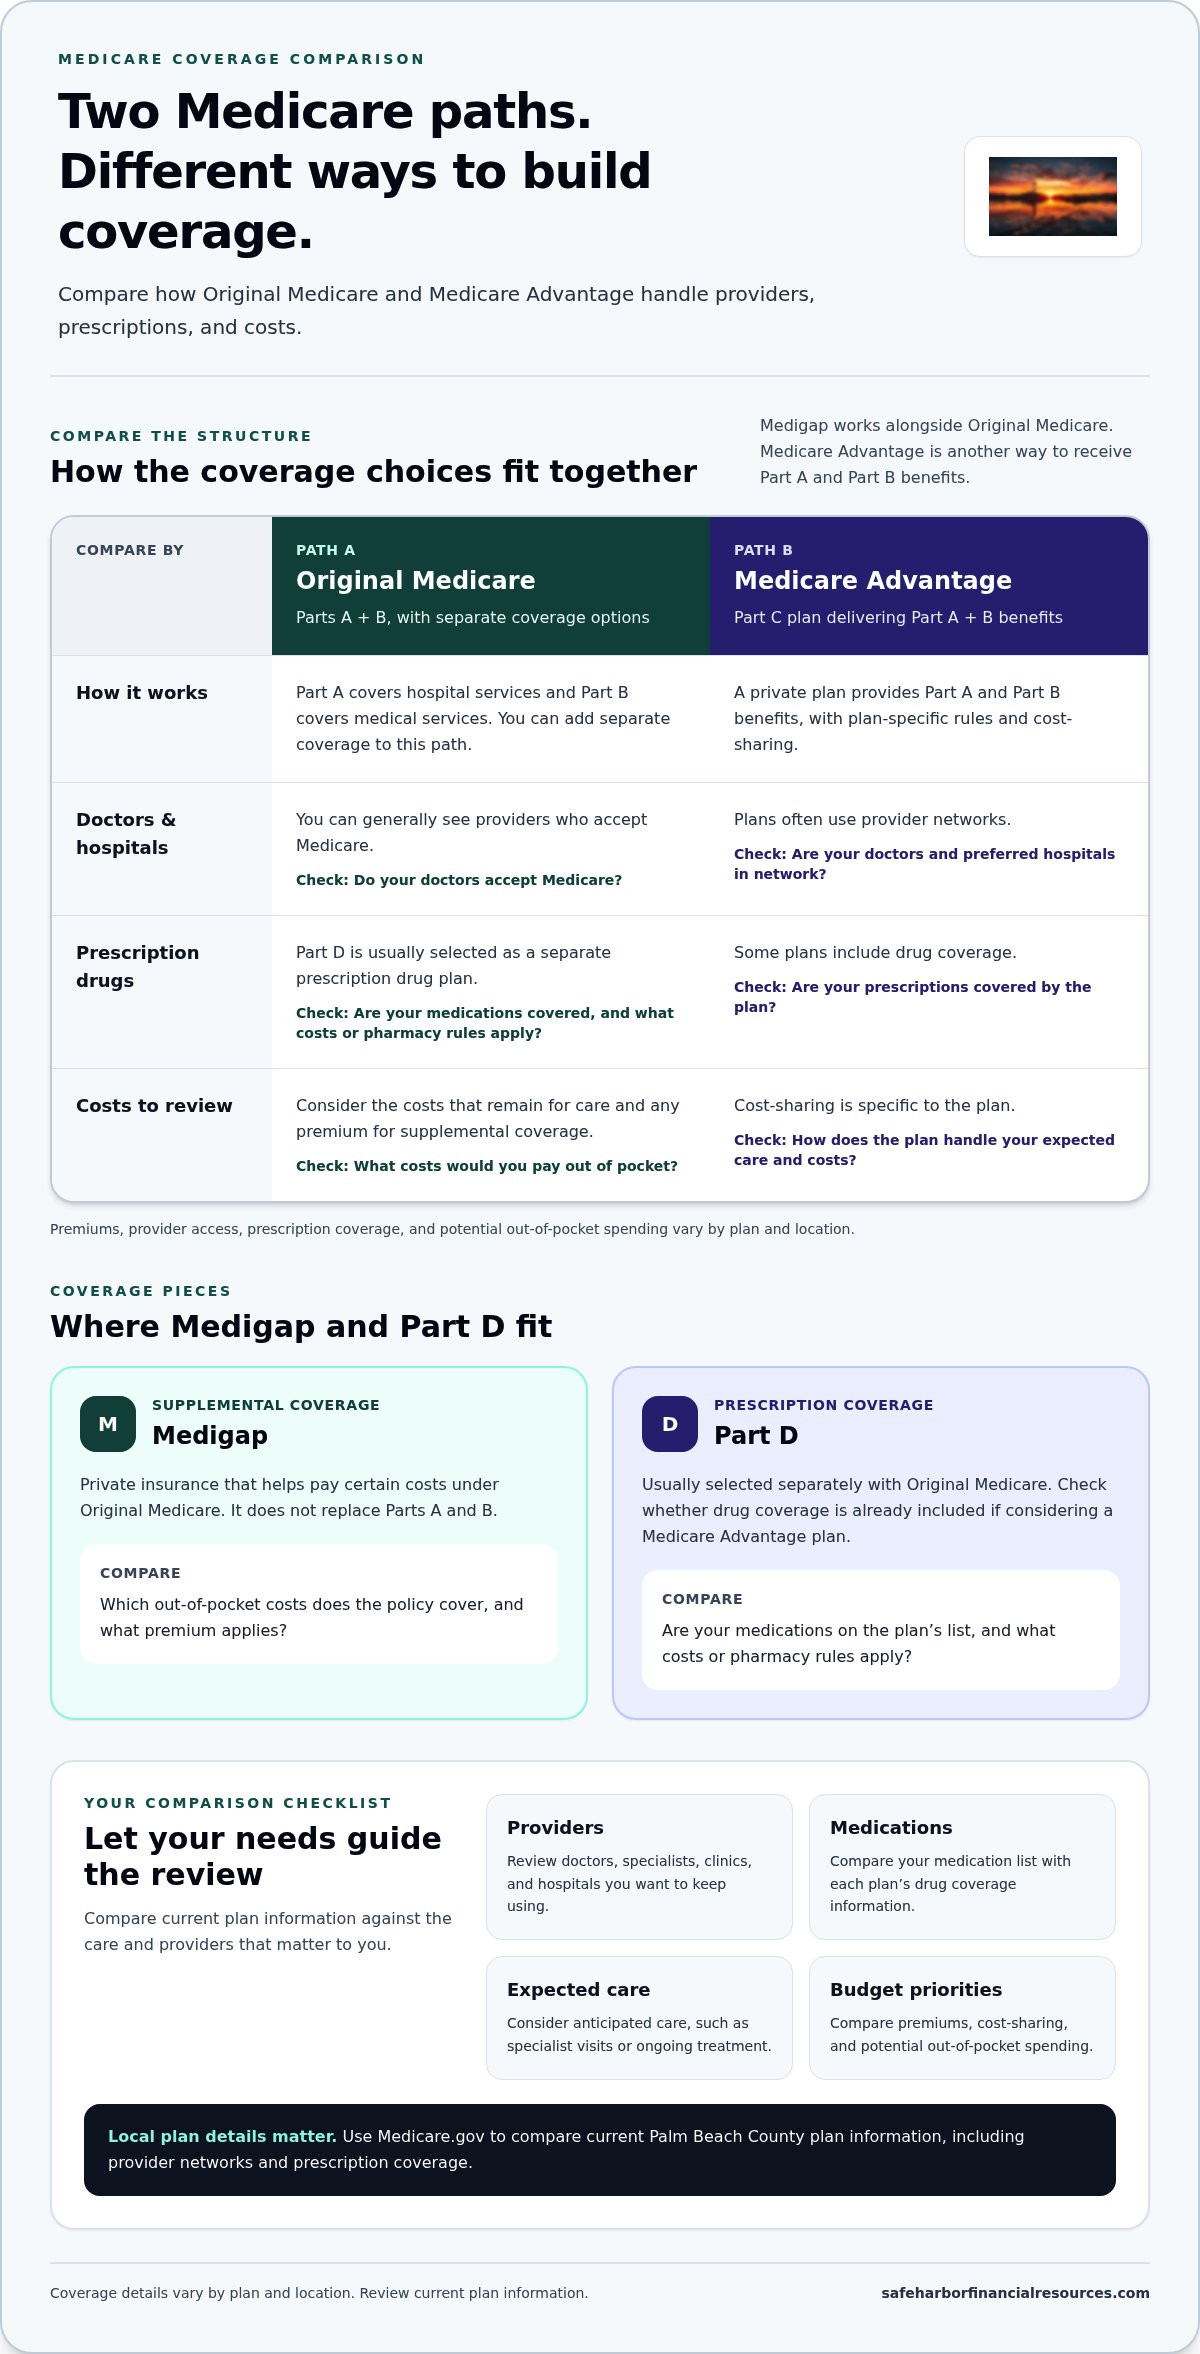
Once you know your timeline, compare how the coverage paths fit together. Original Medicare includes Part A hospital coverage and Part B medical coverage. You can add separate coverage to Original Medicare or choose a Medicare Advantage plan instead. The best fit depends on the providers you want to see, the prescriptions you take, and how you prefer to manage costs.
How do Original Medicare, Medigap, Medicare Advantage, and Part D fit together?
Use this overview to identify what to investigate for your health needs, prescriptions, and preferred providers. Medigap works alongside Original Medicare. Medicare Advantage is a different way to receive Part A and Part B benefits.
Premiums, provider access, prescription coverage, and potential out-of-pocket spending vary by plan and location. Compare current Palm Beach County options using Medicare.gov’s plan information. Review your doctors and medication list against each option, and consider whether you prefer Original Medicare with supplemental coverage or a Medicare Advantage plan. Safe Harbor Financial Resources helps people in Palm Beach Gardens compare Medicare Advantage, Medigap, and Part D considerations. Discuss your Medicare coverage choices with the agency.
Finish your turning-65 checklist and choose a confident next step
Prepare for a Medicare review by gathering details about how you use health care, not just a list of plan features. If you’re deciding what to do when you're about to turn 65, compare options against your everyday needs, the care you anticipate, and the providers you want to keep seeing.
What should you gather before reviewing Medicare coverage?
Keep these details together, on paper or in a secure digital note. They’ll help you compare plan information and ask focused questions about coverage, access, and potential out-of-pocket costs.
Current insurance: Note your plan name, who provides the coverage, and whether it’s tied to your or a spouse’s current employment.
Prescriptions: List each medication’s name, dosage, and how often you take it. Compare the list with each plan’s current drug coverage information.
Preferred clinicians: Write down the doctors, specialists, clinics, and hospitals you want to keep using. Check current plan directories for provider access in Palm Beach County.
Health priorities: Note anticipated care, such as specialist visits or ongoing treatment. Compare how each option handles those needs, cost-sharing, and annual out-of-pocket exposure.
Use Medicare.gov to review current plan information for your location, including provider networks and prescription coverage. Look beyond headline benefits: a feature matters when it fits your doctors, medications, budget priorities, and expected care. If long-term-care planning is also on your mind, include it in your broader financial questions rather than assuming Medicare coverage addresses every future need.
Once your notes are ready, a focused conversation can help you sort through the trade-offs. Safe Harbor Financial Resources helps people in Palm Beach Gardens consider Medicare Supplement Insurance, Medicare Advantage, and Part D as they compare coverage against their priorities.
Make your next Medicare step with confidence
Medicare decisions don’t have to define your 65th birthday. Make time to weigh what matters most, review the details, and choose a path that fits your needs. If you’re still considering what to do when you're about to turn 65, a clear review of your coverage options can help you take the next step with confidence.
Safe Harbor Financial Resources is an independent agency operated by licensed insurance professionals, offering Medicare guidance from Palm Beach Gardens. The agency helps people explore how Medicare Supplement Insurance, Medicare Advantage, and prescription drug coverage may fit their priorities.
Explore a personal Medicare coverage conversation with Safe Harbor Financial Resources. Prepare for your 65th birthday with a clearer understanding of the coverage choices in front of you.
Frequently Asked Questions
When should I apply for Medicare if I’m about to turn 65?
If you’re asking what to do when you're about to turn 65, start by checking when to apply during the seven-month Initial Enrollment Period around your birthday. Your exact dates and coverage start can depend on birthday details, including a first-of-month birthday, and existing coverage. Verify your dates with Medicare.gov or CMS before choosing when to enroll.
Am I automatically enrolled in Medicare when I turn 65?
No, automatic enrollment doesn’t apply to everyone. People already receiving Social Security or Railroad Retirement Board benefits at least four months before turning 65 will likely be enrolled in Parts A and B. Others generally need to apply. Review any enrollment notices for the parts and effective dates shown, then confirm your individual status rather than assuming coverage will start automatically.
Can I keep my employer health insurance after I turn 65?
Possibly. Whether you can keep employer coverage and how it coordinates with Medicare depends on the plan and your employment circumstances. Before delaying enrollment, ask the plan administrator how claims are handled once you become eligible and whether your coverage affects when to enroll. Keep the plan details handy, then verify your next steps with Medicare.gov or CMS.
What happens if I miss my Medicare enrollment window?
The consequences depend on which Medicare coverage you need and why you missed enrollment. You may be able to enroll during the General Enrollment Period or qualify for a Special Enrollment Period, depending on your circumstances. Delayed enrollment can affect coverage timing or costs. Check current CMS guidance promptly and confirm which rules apply to you; don’t assume an exception automatically applies.
Comments