


Guaranteed Issue Life Insurance in Florida: 2026 Guide
Could your health history or age make traditional life insurance harder to secure? For many Florida residents, guaranteed issue life insurance Florida offers a possible path to coverage without medical questions. But acceptance alone doesn’t tell you how much protection a policy provides. Waiting periods, exclusions, and premiums can all affect whether a policy fits your needs.
It’s reasonable to want clear answers before applying. This guide explains what guaranteed issue means, how graded death benefits and exclusions may affect a payout, and how these policies differ from simplified-issue coverage, which may ask health questions. You’ll also learn what terms and costs to compare, along with alternatives such as term and whole life insurance. Understanding the trade-offs can help you decide what to consider next.
What Guaranteed Issue Life Insurance Means for Florida Applicants
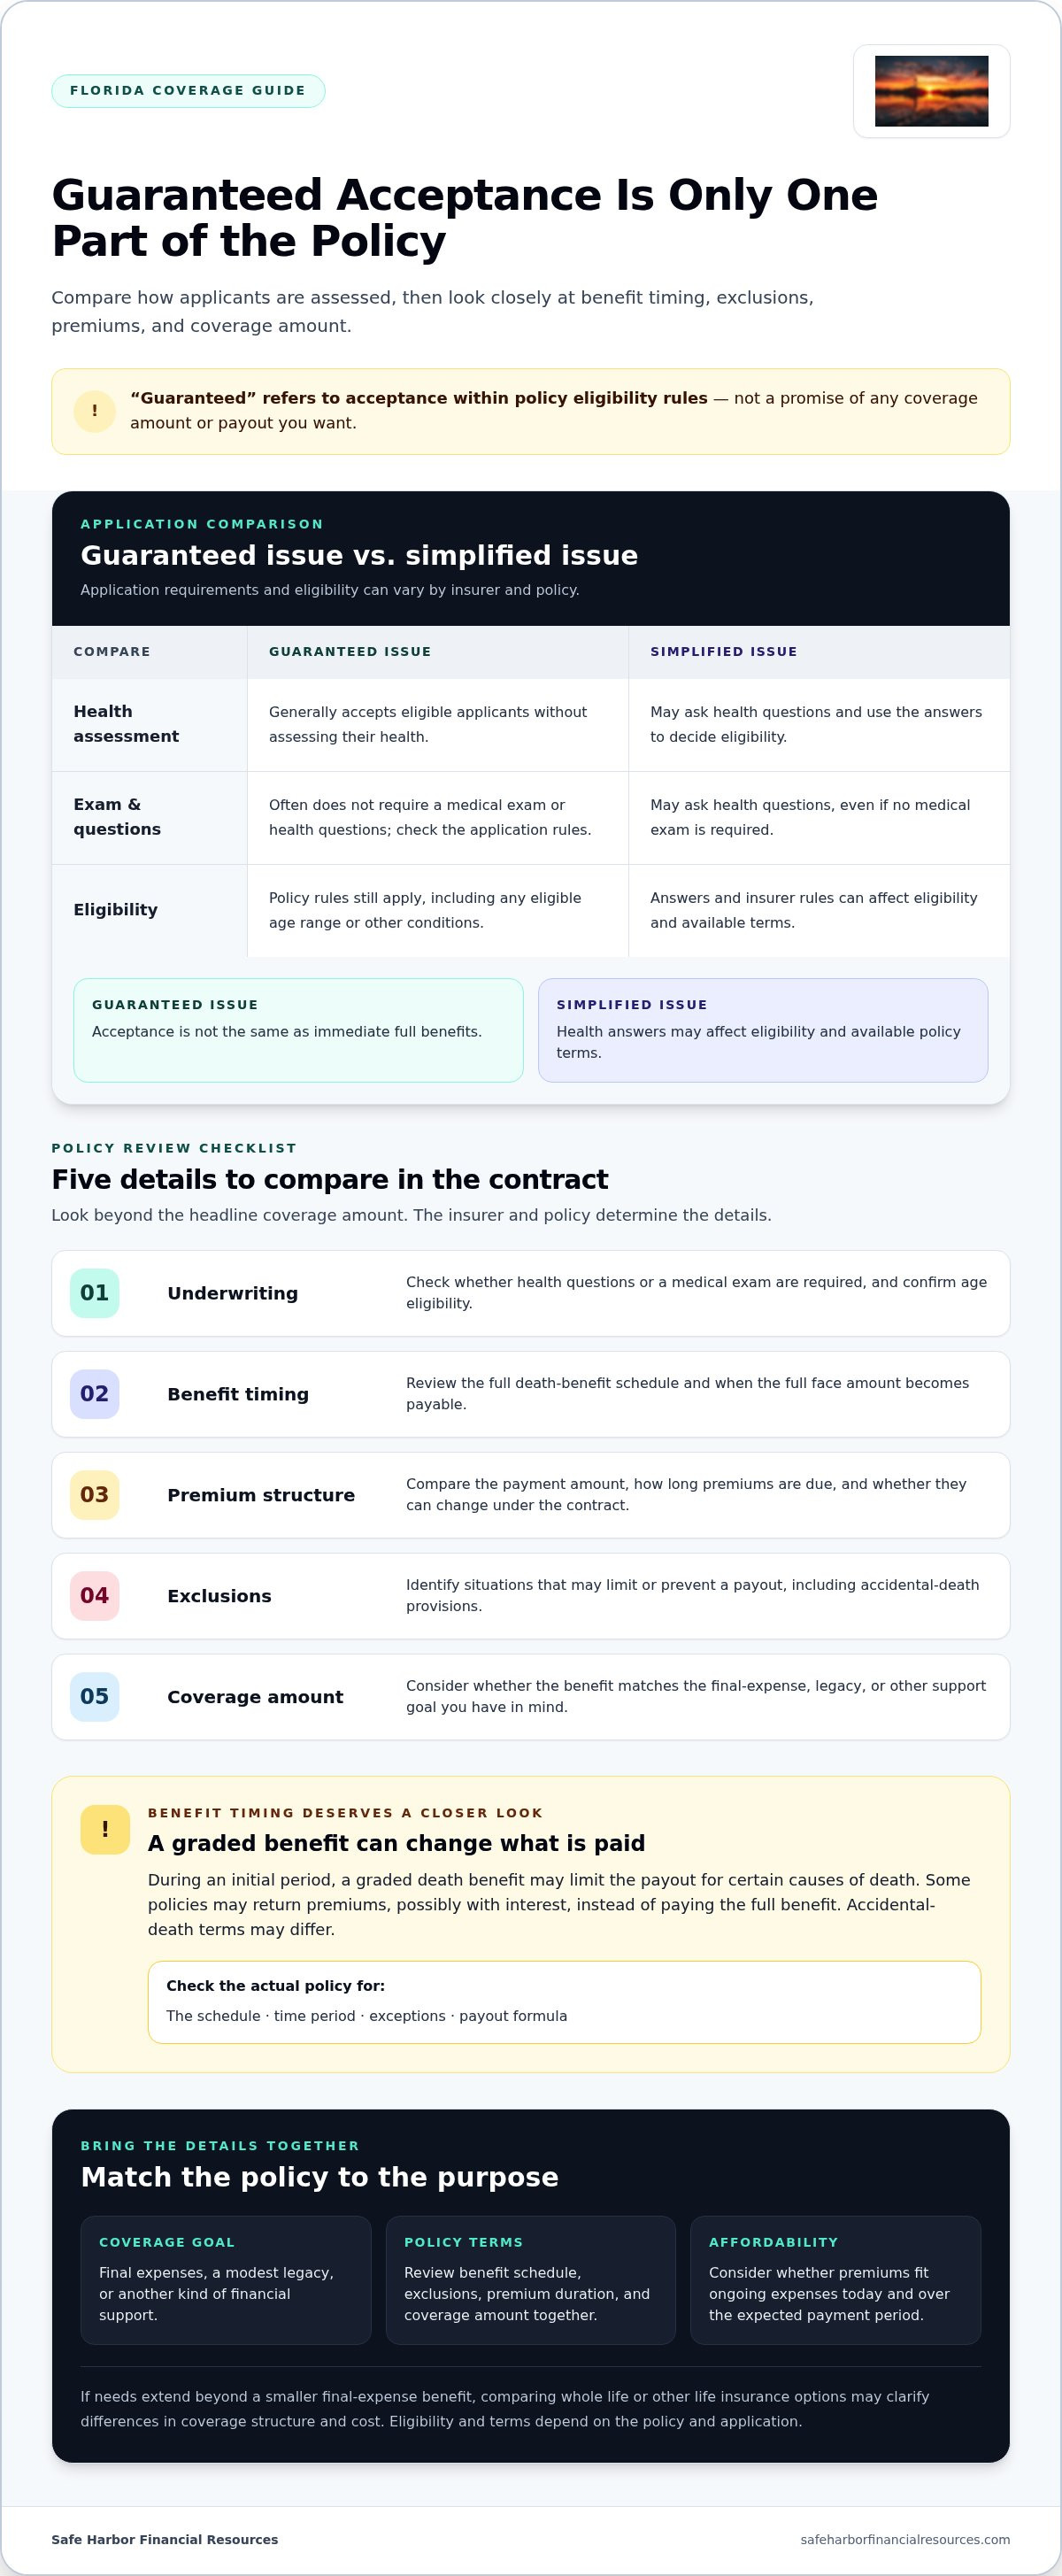
Guaranteed issue life insurance generally accepts applicants who meet the policy’s eligibility rules without assessing their health. That can offer a route to life insurance when health history makes medically underwritten coverage difficult to obtain. But “guaranteed” refers to acceptance within those rules, not to any coverage amount or payout a person wants.
Guaranteed issue means eligible applicants aren’t turned down based on their health; simplified issue may ask health questions and use the answers to decide eligibility. For a general overview, see Guaranteed Issue Life Insurance Explained.
For Florida applicants, details still depend on the insurer and contract. Age limits determine who may apply, while exclusions and benefit timing affect when and how much a beneficiary could receive. Review the policy itself rather than assuming every plan uses the same terms. The available face amount and the conditions attached to it matter as much as the application process.
Does guaranteed issue mean there are no health questions?
Often, guaranteed issue policies don’t require medical exams or health questions. Application and eligibility rules can vary by insurer, however. A policy may set an eligible age range or other conditions, so read the application materials and contract carefully.
Simplified-issue coverage is different: it may ask health questions, even if it doesn’t require a medical exam. Depending on the answers and the insurer’s rules, eligibility and available terms may differ. When comparing options, focus on what each application asks and how the policy defines eligibility, exclusions, and benefits.
The Florida Office of Insurance Regulation is a state information resource for understanding insurance oversight. Its Life and Health Product Review Unit reviews policy forms and rates for compliance with Florida law, but the contract explains the terms of an individual policy.
How to Compare Guaranteed Issue Life Insurance in Florida
Guaranteed acceptance can make applying feel simpler, but it doesn’t automatically mean immediate full benefits or good value. Compare policy terms side by side. Pay particular attention to how long premiums are due and what your beneficiary could receive at different points in time.
A graded death benefit may limit the payout for certain causes of death during an initial period. Some policies return premiums, possibly with interest, instead of paying the full benefit; accidental-death terms may differ. Read the policy’s schedule, time period, exceptions, and payout formula rather than relying on a general description.
What policy details should you review before applying?
Read the full benefit schedule, waiting-period language, exclusions, and accidental-death provisions. Confirm how long premiums are payable, then consider whether the benefit suits your intended final expense or legacy need. Guaranteed issue policies in Florida can differ on each point, so compare the contract terms, not just the headline coverage amount.
Life insurance and long-term-care planning address different needs. For a separate look at Florida nursing home cost planning, consider how care costs fit into your broader financial picture. A careful review with a licensed insurance professional can also help clarify how policy terms relate to your goals.
Choosing a Life Insurance Next Step in Palm Beach Gardens
Once you understand the policy trade-offs, start with the purpose of the coverage, not just the application process. This checklist can help organize your decision:
Identify the goal. Decide whether you want to help with final expenses, leave a modest legacy, or provide another kind of financial support.
Compare policy terms. Review the benefit schedule, exclusions, premium duration, and coverage amount together. A larger face amount may not be useful if the cost strains your budget.
Review affordability. Consider whether premiums fit comfortably into your ongoing expenses, both today and over the period you expect to pay them.
If your needs extend beyond a smaller final-expense benefit, comparing whole life or other life insurance options can help clarify differences in coverage structure and cost. Term, whole life, and policies with living benefits serve different purposes, and eligibility and terms depend on the policy and application. Comparing them doesn’t promise approval, but it can show whether guaranteed issue life insurance Florida fits your priorities or whether another option merits consideration.
How can a local review make the decision clearer?
A local insurance professional can explain policy language and help you weigh trade-offs against your coverage goals and budget. Safe Harbor Financial Resources is an independent Palm Beach Gardens agency offering personalized guidance on life insurance choices. Before a conversation, note your coverage goal, budget considerations, and questions about terms such as waiting periods or exclusions. Learn more about life insurance choices with Safe Harbor Financial Resources.
Move Forward With a Clearer Coverage Plan
Guaranteed issue life insurance can offer a path to coverage when health concerns make other applications challenging, but acceptance doesn’t necessarily mean immediate full benefits or the right fit for every goal. Before deciding, compare the benefit schedule, exclusions, premium structure, and coverage amount. Consider whether whole life or another life insurance option better aligns with your needs and budget.
Understanding guaranteed issue life insurance Florida policies is easier when you can discuss the details in context. Safe Harbor Financial Resources is an independent agency owned and operated by licensed insurance professionals in Palm Beach Gardens, providing guidance on insurance and retirement choices. Discuss your life insurance options with a local professional at Safe Harbor Financial Resources.
A considered next step can bring greater clarity and help you choose coverage with confidence.
Frequently Asked Questions
Is guaranteed issue life insurance available in Florida?
Yes, guaranteed issue life insurance is available to eligible applicants in Florida, including Palm Beach Gardens residents. These policies generally don’t use health questions or medical exams to decide acceptance, but age and other eligibility rules still apply. Insurers set their own limits and terms, so review the specific policy rather than assuming every Florida plan works alike.
Can you be denied guaranteed issue life insurance because of a health condition?
Usually, a health condition alone won’t disqualify an applicant who meets the policy’s eligibility rules, because guaranteed issue coverage is designed to accept eligible applicants without medical underwriting. Acceptance isn’t unconditional, however: age limits and other application requirements still apply. Read the application and contract carefully. If health questions may be manageable, comparing simplified-issue or other life insurance options could also be worthwhile.
What happens if you die during a guaranteed issue policy waiting period?
The payout depends on the policy and the cause of death. Many policies have a two-year graded-benefit period. If death from natural causes occurs during that period, the beneficiary may receive premiums paid plus about 10% interest instead of the full face amount. Accidental death may be covered for the full amount sooner, but check the contract’s definitions and exceptions.
How much guaranteed issue life insurance coverage can you get in Florida?
Guaranteed issue policies in Florida typically offer coverage from about $2,000 to $25,000, though the available amount varies by insurer and policy. These plans are often intended to help with final expenses or leave a modest legacy. Consider whether the benefit fits your goal and whether the premiums remain affordable over time.
Comments