


Secure Retirement Income Solutions: A Practical Guide to Your Options
What if dependable retirement income didn’t mean giving up all your flexibility? It’s understandable to wonder how long your savings will last, especially when market changes could affect planned withdrawals and annuity features can be difficult to compare. Secure retirement income solutions don’t have to be an all-or-nothing choice.
A retirement income plan can bring different sources together, such as Social Security, savings, and annuities, to balance reliability with access to your money. This guide compares common options, explains their potential guarantees and trade-offs, and outlines what to review before choosing an approach. You’ll also see how fixed and fixed indexed annuities may fit into a broader plan, without treating either as the right answer for everyone. With a clearer view of your priorities, you can make more informed decisions about an income strategy that fits your goals.
Secure retirement income solutions start with a clear income plan
Secure retirement income isn’t a single product or promise. It’s a plan for covering your needs over time, with a clear view of which income sources are relatively predictable and which may change. Social Security or a pension may provide a steady base, while withdrawals from savings can vary with market performance, spending choices, and how long the money needs to last.
Start by separating essential costs, such as housing and healthcare, from flexible goals like travel or gifts. Then consider your time horizon, health, and comfort with risk. A longer retirement may call for a different balance of accessible savings and predictable income than a shorter one. The Retirement Planning Overview also outlines how income sources and withdrawal choices fit into broader retirement planning.
This video offers another perspective on Social Security and retirement income strategy:
How can retirement income sources work together?
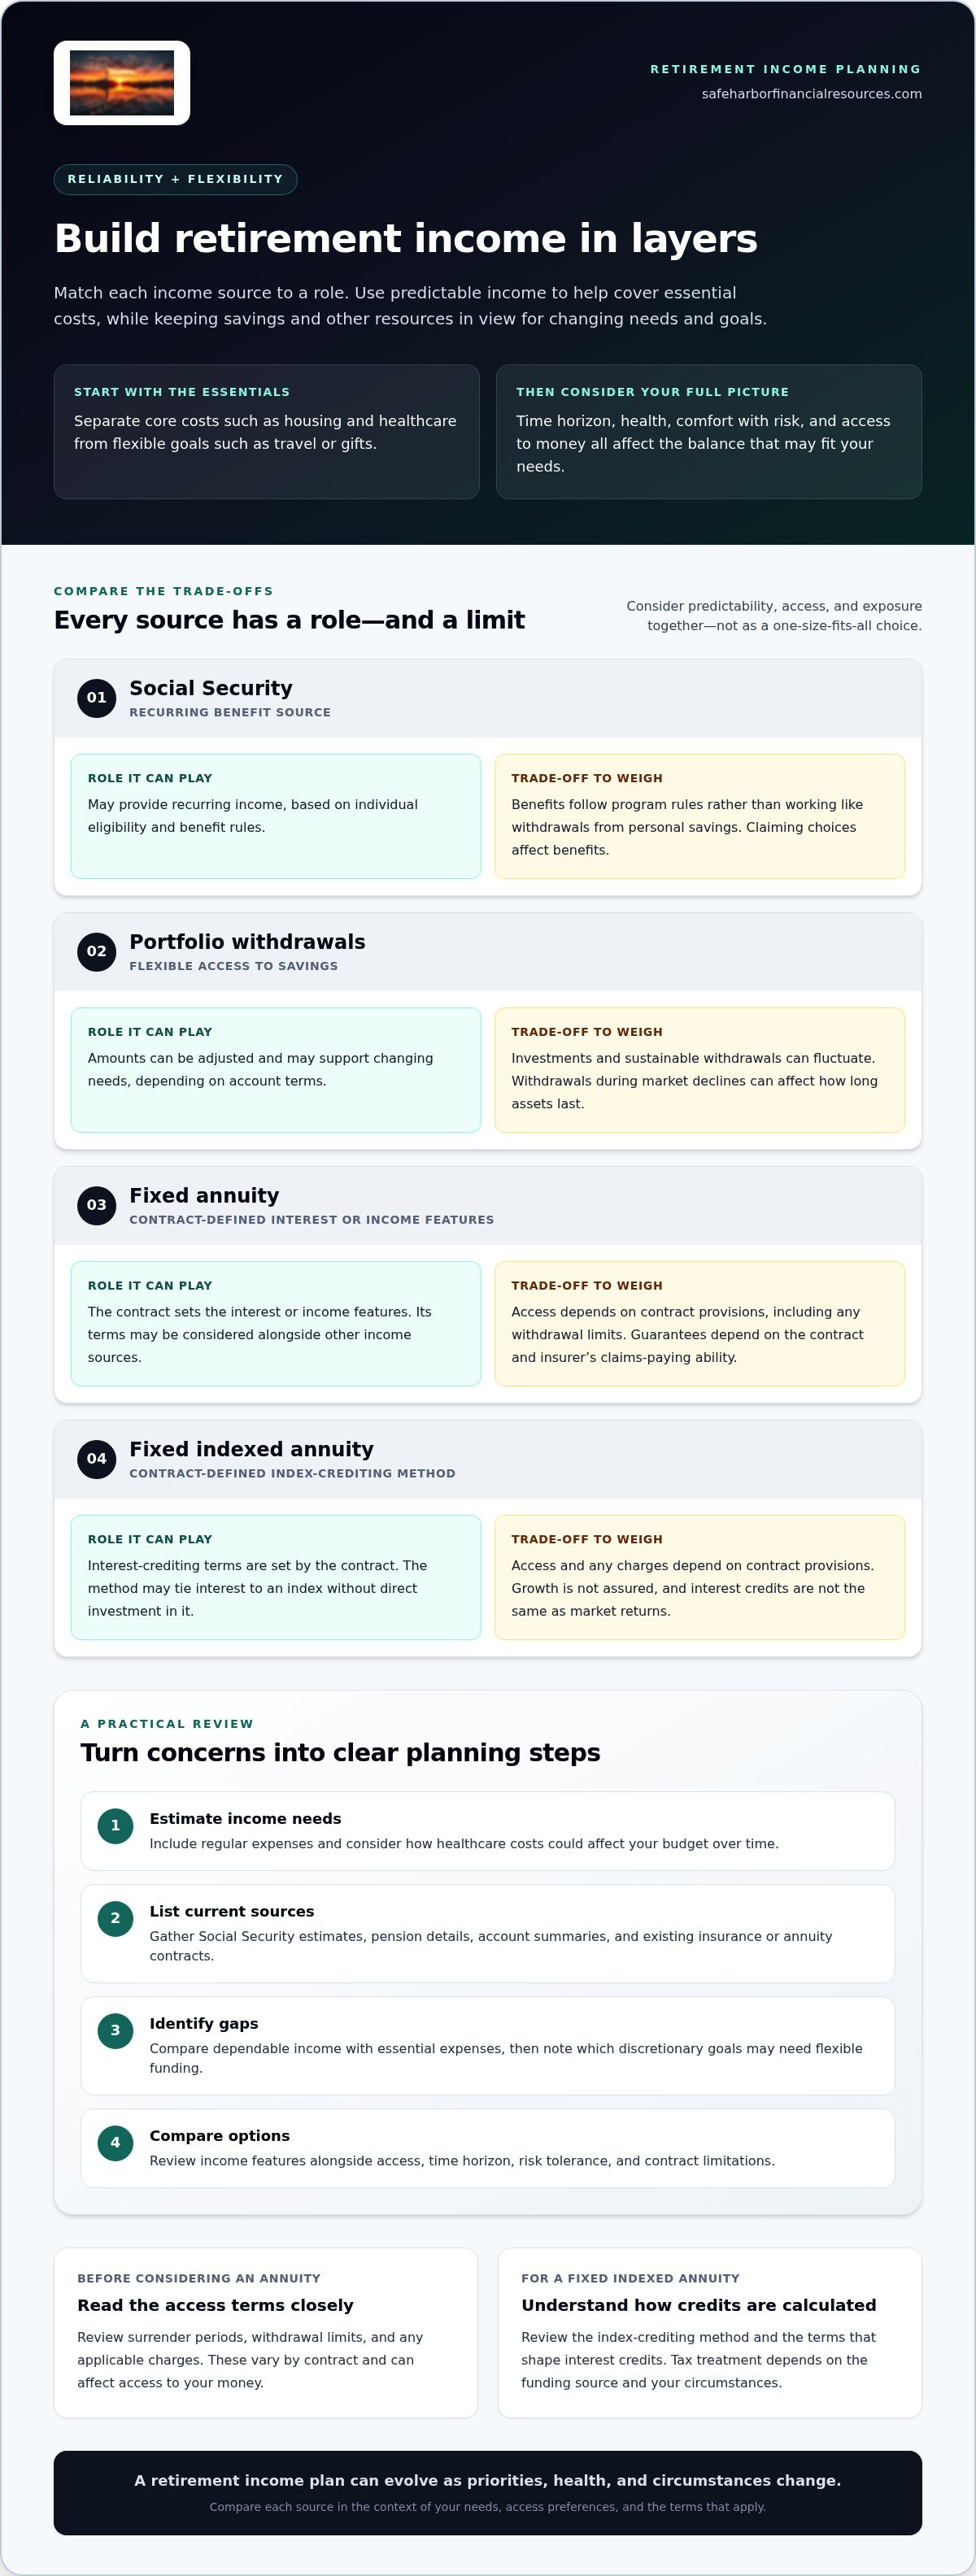
Think in layers, matching each source to a role rather than expecting one option to do everything. For example, predictable income could help meet core bills, while savings withdrawals support changing needs and personal goals. Fixed and fixed indexed annuities may be considered as part of that broader picture, but their features and contract terms differ.
Social Security and pensions: Potential sources of recurring income, subject to their own eligibility rules and payment provisions.
Savings withdrawals: Can offer access and choice, but balances and withdrawal sustainability may be affected by markets and spending.
Annuities: Contract protections depend on the specific terms and issuing insurer. Access, limitations, and income features vary.
Secure retirement income solutions should reflect your household’s full picture. In Palm Beach Gardens, Safe Harbor Financial Resources provides guidance on comparing fixed and fixed indexed annuity features with your income needs, while keeping flexibility and each source’s limitations in view.
Compare retirement income solutions by predictability, access, and risk
Each income source balances reliability and flexibility differently. Use the comparison below to consider how secure retirement income solutions may complement one another, rather than treating any option as a universal fit.
For a broader look at retirement resources and planning topics, the U.S. Department of Labor Retirement Toolkit offers useful background.
What trade-offs should you review before considering an annuity?
Read the contract’s liquidity provisions closely. Surrender periods, withdrawal limits, and any applicable charges vary by contract and can affect access to your money. For a fixed indexed annuity, review how the index-crediting method works and which terms shape interest credits. The annuity doesn’t invest directly in the index, and credits aren’t the same as market returns. Tax treatment also depends on the funding source and your circumstances, so include qualified tax guidance in your review.
Safe Harbor Financial Resources provides personalized annuity guidance in Palm Beach Gardens to help you compare contract features with your income needs. Explore retirement income guidance as you consider your options.
Choose next steps for a retirement income strategy in Palm Beach Gardens
A practical review can turn broad concerns into clear questions. Estimate what you’ll spend, separating essential bills from goals where spending can adjust. Then list current income sources and savings, identify any shortfall, and compare options that could address it. This sequence keeps secure retirement income solutions connected to your needs, not just product features.
Estimate income needs: Include regular expenses and consider how healthcare costs could affect your budget over time.
List current sources: Gather Social Security estimates, pension details, account summaries, and existing insurance or annuity contracts.
Identify gaps: Compare dependable income with essential expenses, then note which discretionary goals may need flexible funding.
Compare options: Review potential income features alongside access, time horizon, risk tolerance, and contract limitations.
For Social Security planning, the Social Security Retirement Benefits page explains benefit information and factors to consider. Keep your estimate with the rest of your planning materials.
What should you bring to an income-planning conversation?
Bring current income estimates, account summaries, spending priorities, and details of any existing annuity or insurance contracts. Note when you may need access to funds and which expenses call for dependable coverage versus flexibility. If long-term care is a concern, include expected healthcare needs in the discussion and consider how they may affect your income plan.
Safe Harbor Financial Resources provides personalized annuity guidance in Palm Beach Gardens, helping you discuss fixed and fixed indexed annuity features in the context of your broader income needs. A conversation can clarify trade-offs without promising a particular outcome. Explore personalized retirement income guidance as a next step.
Take a confident next step toward retirement
Your retirement income plan can evolve as your priorities, health, and circumstances change. You don’t need every answer today. A thoughtful next step is to clarify what matters most to you and explore options with that goal in view.
Safe Harbor Financial Resources is a Palm Beach Gardens-based agency owned and operated by licensed insurance professionals. Its guidance on fixed and fixed indexed annuities can help you consider contract features as part of your broader income strategy, without assuming one approach suits everyone. The aim is greater clarity as you weigh secure retirement income solutions against your personal needs and preferences.
Discuss your retirement income options with Safe Harbor Financial Resources and take a steady, informed step toward the retirement you want.
Frequently Asked Questions
Are annuities a secure retirement income solution?
An annuity can be part of a secure retirement income solution, but it isn’t automatically right for every household. The contract defines what income or other protections apply, and insurer-backed obligations depend on the issuing insurer’s claims-paying ability. Consider how a payout option could affect access to your money, your spouse or beneficiaries, and the income you may need later.
Can you lose money in a fixed indexed annuity?
Potentially, depending on the contract and how funds are used. A fixed indexed annuity isn’t a direct investment in an index, so an index decline doesn’t necessarily translate into an equivalent account loss; the crediting formula determines interest for a period. Withdrawals, applicable charges, or surrender provisions may reduce value. Review the contract’s examples and limits before deciding.
How do I compare retirement income solutions?
Compare secure retirement income solutions against the same real-life tests: a routine month, a large unplanned expense, and an extended period of market weakness. Note income timing, access restrictions, inflation sensitivity, tax treatment, and what happens to a surviving spouse. In Palm Beach Gardens, personalized guidance from Safe Harbor Financial Resources can help organize these questions without treating one option as a universal winner.
Does an annuity replace Social Security or a pension?
No. An annuity is a separate contract and doesn’t become a Social Security benefit or employer pension. It may be considered alongside those sources as another income component, but its terms, access rules, and insurer backing differ. For example, compare its stated payment arrangement with your existing benefit start dates and household needs before deciding whether the pieces work together.
Comments