


Medigap Cost at 65 in Florida: Compare Prices and Plan Choices
Switching Medigap plans outside Open Enrollment may be possible, but your health history can affect your options. How much Medigap costs at age 65 in Florida depends on the plan, insurer, location, and rating factors. According to the Centers for Medicare & Medicaid Services, Florida’s Medigap Open Enrollment lasts six months and begins on the first day Medicare Part B coverage begins.
It’s understandable to want a clear premium and confidence that you can change plans later. Outside that enrollment period, an insurer may use medical underwriting if you don’t have a guaranteed issue right, which can affect eligibility or the premium. This guide explains how plan benefits and rating factors shape costs, what health history may mean for your choices, and how switching rules work, so you can compare options with a steadier view of the decision.
Differences between Medigap plan benefits and costs
Florida offers 12 Medigap plans, with different coverage choices. Benefits for each lettered plan are standardized, but premiums can vary by insurance company and location.
Choosing a Plan for Needs and Budget
Start with the coverage you want, then weigh the premium against possible out-of-pocket costs. Plan G doesn’t cover the Medicare Part B deductible, which can affect your spending even with a Medigap policy. A lower monthly premium may suit a tighter budget, while a plan with different cost-sharing may better fit someone prioritizing predictable expenses.
The right balance depends on the benefits you value and the costs you’re prepared to pay yourself. Compare the same lettered plan across insurance companies so price differences don’t obscure coverage differences.
Plan G and Plan N Premiums in Palm Beach Gardens
Plan G and Plan N premiums in Palm Beach Gardens depend on local rating factors and the insurer. Florida-wide sample figures aren’t a local quote, so compare current rates for your area to understand your options.
Plan G and Plan N have standardized benefits for their letter, but premiums can differ between insurers. A quote for one ZIP code may not apply elsewhere in Palm Beach County.
Choose a plan whose benefits and cost-sharing fit your needs, then compare premiums for that same plan and location.
Does my health history affect my Medigap premium or eligibility?
Yes, health history can affect eligibility or premiums when medical underwriting applies. Other rating factors include plan, insurer, location, and tobacco status.
Medicare Advantage and Medigap have different coverage and cost structures. Compare monthly premiums alongside potential out-of-pocket expenses to see how each fits your budget in Palm Beach Gardens.
Factors Affecting Medigap Premiums
A Medigap premium can vary by insurance company, ZIP code, plan, and rating factors. In Palm Beach Gardens, compare quotes using the same plan and applicant profile. Tobacco status can also affect the premium: tobacco users are typically charged 5% to 50% more than non-tobacco users for the same plan.
For a 65-year-old female nonsmoker, matching the plan and location across quotes helps make the comparison useful. It also helps distinguish insurer pricing from profile differences.
Medical Underwriting and Premium Differences
Medical underwriting may affect an application outside Medigap Open Enrollment if no guaranteed issue right applies. An insurer may review health information and use it to decide whether to accept an application or set a premium. This differs from plan benefits, which are standardized for each lettered plan.
To compare current Palm Beach Gardens rates, use quotes for the same plan, ZIP code, age, and tobacco status. Include applicable discounts so the premium differences are easier to assess.
Original Medicare and Medicare Advantage have different cost structures. Medigap works alongside Original Medicare and may cover certain cost-sharing, such as coinsurance, according to the plan. Compare premiums and likely out-of-pocket costs for the coverage arrangement that fits your care needs.
Can I switch Medicare Supplement plans outside of Open Enrollment?
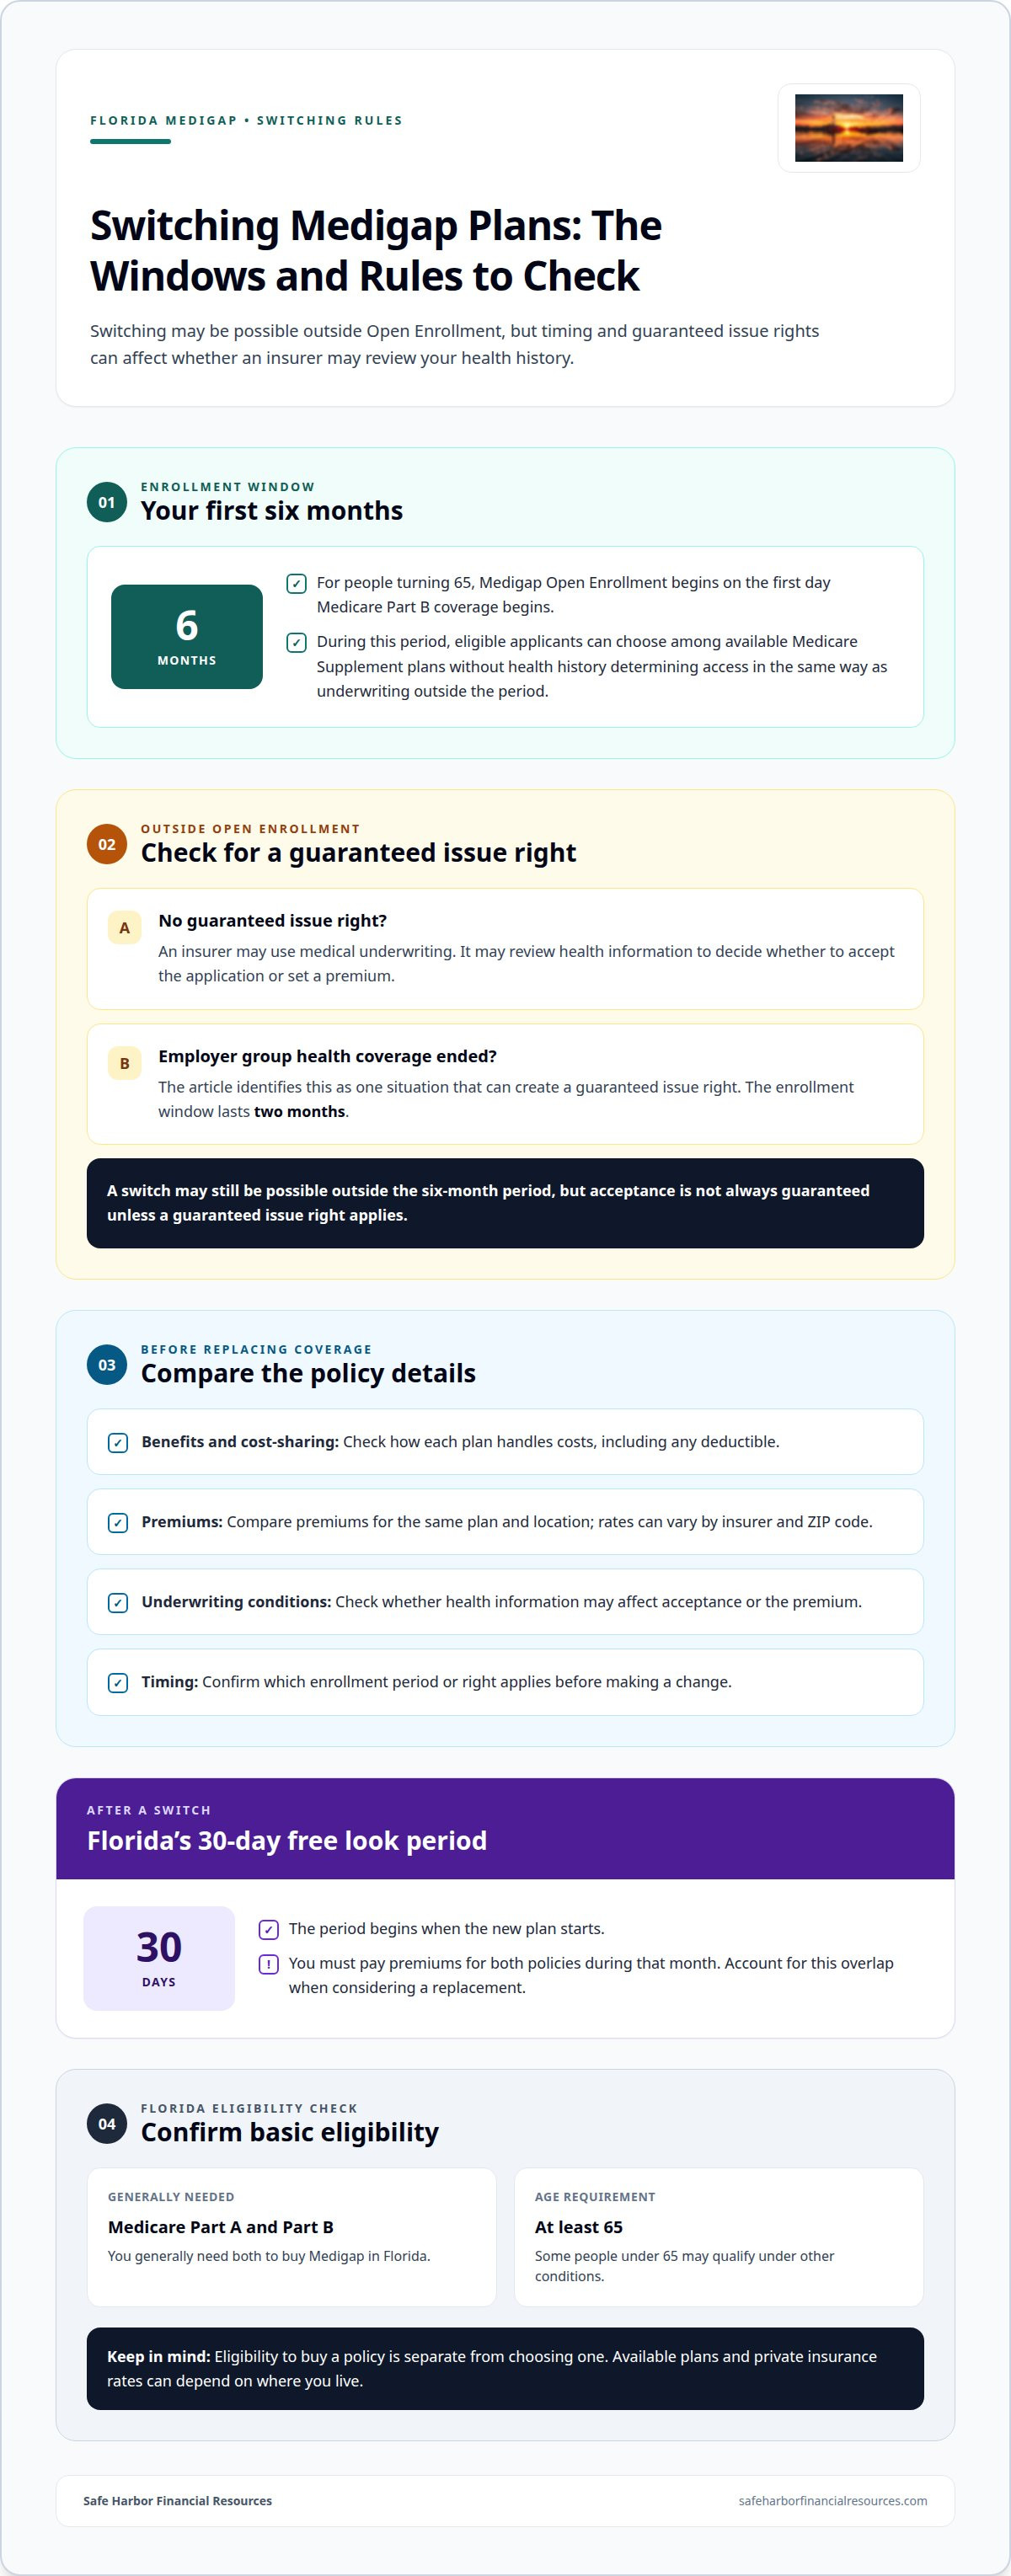
Yes, switching outside Open Enrollment may be possible, but acceptance for a new policy isn’t always guaranteed. Without a guaranteed issue right, an insurer may use medical underwriting or charge a different premium.
For people turning 65, the six-month Medigap Open Enrollment Period begins on the first day Medicare Part B coverage begins, according to the Centers for Medicare & Medicaid Services. During this period, eligible applicants can choose among available Medicare supplement plans without health history determining access in the same way as underwriting outside the period.
To buy Medigap in Florida, you generally need Medicare Part A and Part B and must be at least 65. Some people under 65 may qualify under other conditions. Eligibility is separate from choosing a policy: the available medigap plans and private insurance rates can depend on where you live.
Outside the six-month period, a Florida resident may still switch, but underwriting can affect acceptance or premiums unless a guaranteed issue right applies. One such right follows the termination of employer-based group health coverage and lasts two months. This protection creates a specific window to enroll in another Medicare Supplement plan.
After switching, Florida provides a 30-day free look period beginning when the new plan starts. You must pay premiums for both policies during that month, so account for the overlap before replacing existing coverage. Check how each plan handles cost-sharing, including any deductible, before deciding.
When considering a switch, compare benefits, premiums, underwriting conditions, and the timing of your enrollment rights. This helps clarify whether a lower premium also means different out-of-pocket costs or fewer protections.
Safe Harbor Financial Resources: Medicare Supplement Insurance (Medigap)
Safe Harbor Financial Resources offers Medicare Supplement Insurance (Medigap) and helps Floridians make sense of plan choices. If you’re weighing premiums, benefits, or a possible switch, guidance can help you compare how coverage options fit your health needs and budget.
Medigap is one part of a broader insurance picture. Safe Harbor Financial Resources also offers Life Insurance with Living Benefits, Term Life Insurance, and Whole Life Insurance for people considering additional protection.
When you’re ready to discuss Medigap choices alongside your Medicare coverage, Safe Harbor Financial Resources can help you understand your options. Contact the team for a free Medicare consultation, with no pressure.
Take the Next Step Toward Confident Coverage
Choosing coverage is also a chance to set a clear direction for your healthcare budget. If you’re still weighing how much Medigap costs at age 65 in Florida, focus on the balance between the benefits you value and the premium you can manage. Then consider how your enrollment timing and health history may shape your options.
Safe Harbor Financial Resources offers Medicare Supplement Insurance (Medigap), Life Insurance with Living Benefits, and Term Life Insurance. A conversation can help you consider how these options relate to your priorities while keeping the coverage decision in focus.
Contact Safe Harbor Financial Resources to discuss your next step. You can move forward with greater clarity, one decision at a time.
Frequently Asked Questions
Do Medicare Supplement premiums ever go up?
Yes, Medigap premiums may increase over time, so your initial monthly amount may not remain unchanged. Your premium may be tied to factors set when you enroll, but it can still increase over time. When planning your budget, account for the ongoing premium rather than treating your enrollment quote as a fixed lifetime amount.
What is the downside to Medigap plans?
A key drawback is paying a separate premium alongside your Medicare Part B premium, even during months when you use little care. Medigap also doesn’t cover prescription drugs or Medicare Part D copayments, so you’ll need to account for prescription coverage separately. Some cost-sharing may remain, depending on the plan, so a lower premium doesn’t always mean lower total spending.
Why is Medigap so expensive in Florida?
The question of how much Medigap costs at age 65 in Florida has no single statewide answer. Premiums vary by plan, insurer, and location, while health status may matter when underwriting applies. For example, a quote in Palm Beach Gardens reflects local rating factors and the applicant’s profile. Comparing the same plan letter and profile makes price differences easier to understand.
How do insurance companies set prices for Medigap policies?
Insurers set premiums using factors such as plan choice, location, tobacco status, and applicable rating rules. Discounts may also affect a quote, including those tied to household circumstances or payment method. Since benefits for a given lettered plan are standardized, comparing the same plan across insurers helps separate premium differences from coverage differences.
How does this affect cost?
Florida uses issue-age rating, so the premium’s age basis is set by the age when you first enroll. It doesn’t rise solely because you grow older, but the premium can still change for other reasons, including general rate increases. When reviewing a renewal notice, distinguish an age-based change from a carrier’s broader premium adjustment.
Comments