


Fixed Indexed Annuities and Retirement Asset Protection
Market-linked growth doesn’t have to mean taking the full impact of a market decline. For those focused on protecting retirement assets with fixed indexed annuities, the key is understanding the contract’s interest-crediting floor: some contracts won’t credit less than 0% interest when the linked index falls. That can limit losses tied to index performance, but withdrawals and contract charges can still reduce the value you receive.
It makes sense to seek growth potential without exposing retirement savings directly to stock-market losses. The details matter: caps and participation rates can limit interest credited when an index rises, while withdrawal rules affect how the protection works in practice.
This article explains why people consider fixed indexed annuities, how index-linked growth and principal protection work, and how you can lose money. You’ll also learn what to consider when weighing an annuity against your retirement goals.
Why an indexed annuity?
Fixed annuities generally credit a stated rate, while variable annuity returns are tied to investment performance and can fluctuate. Fixed indexed annuities credit interest using an index formula, subject to contract limits. Bonds are debt investments whose market values can change before maturity.
People may consider an indexed annuity for index-linked growth potential and a contract-based floor, rather than direct stock-market investment. Guarantees depend on the issuing insurer’s financial strength and claims-paying ability.
Optional Income and Death-Benefit Riders
An income rider can add a contractual lifetime income benefit, while a death-benefit rider specifies what beneficiaries may receive. These optional features can matter when retirement income or a transfer to loved ones is part of the plan. A financial advisor can explain how each rider’s terms affect the contract. Many annuities also offer death benefits that may help beneficiaries avoid probate-related delays and complications.
Tax-Deferred and Income Annuities
A tax-deferred annuity lets interest grow tax-deferred until it is withdrawn, while an income annuity is designed to turn premium into payments. This distinction matters when balancing future growth against retirement income needs. Taxable annuity income is generally treated as ordinary income; according to the Internal Revenue Service, ordinary income taxes can currently reach 37 percent. The Federal Deposit Insurance Corporation states that FDIC protection for bank accounts is up to $250,000. Annuity guarantees are not FDIC-insured; they depend on the issuing insurer’s financial strength.
Payout Options and Lifetime Income
Annuity payouts may run for a fixed term, such as 10 or 20 years, or continue for the annuitant’s lifetime. The choice shapes how long payments last and whether income continues for a surviving beneficiary. Some fixed indexed annuities offer protected lifetime income benefits through optional riders. Those benefits can support predictable retirement income, while the contract’s index-crediting method determines growth potential before payouts begin.
Can you Lose Money in an Annuity?
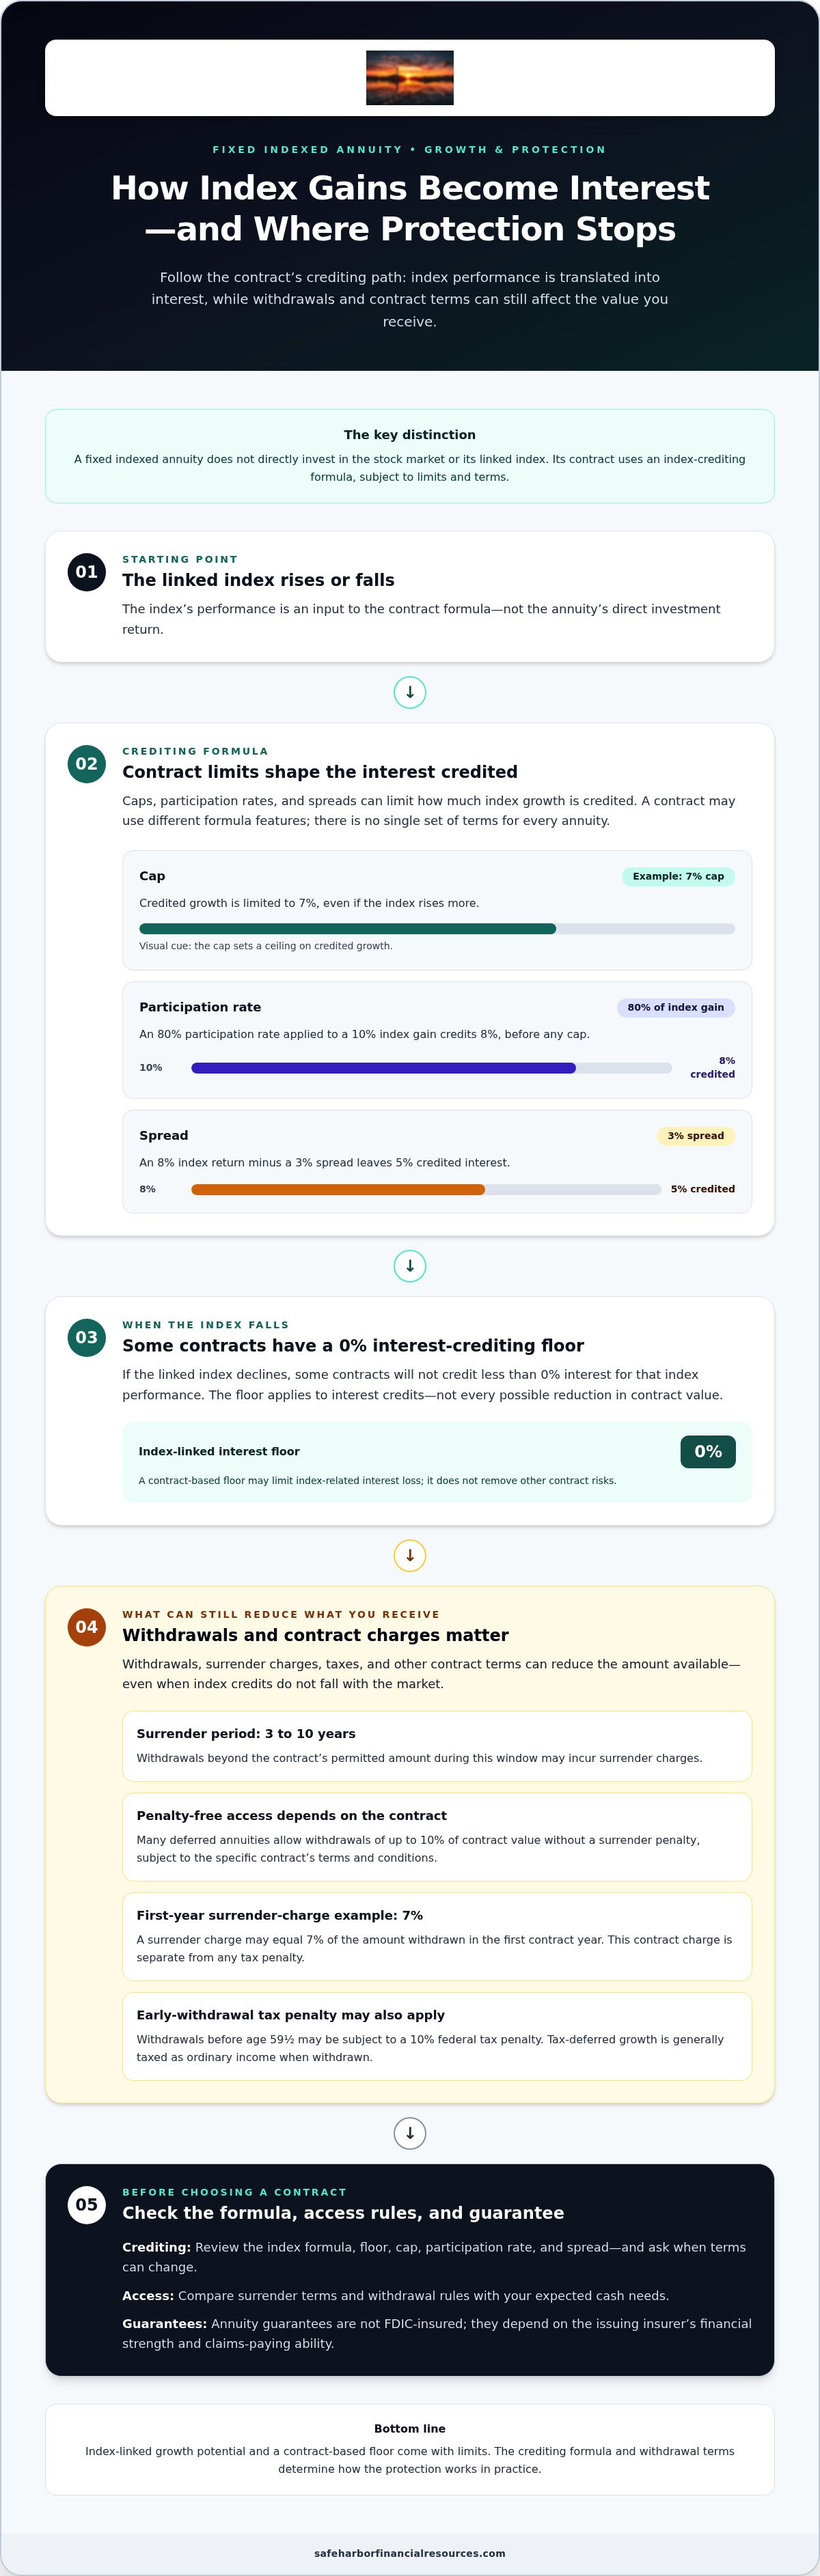
Yes. Withdrawals, surrender charges, and taxes can reduce what you receive, even when the contract’s index credits don’t fall with the stock market. Timing matters, especially if you may need savings before the surrender period ends.
Early-Withdrawal Penalties and Charges
Taking money from an annuity can trigger a tax penalty, a contract charge, or both. According to the Internal Revenue Service, withdrawals before age 59½ may be subject to a 10% federal tax penalty. Tax-deferred growth is generally taxed as ordinary income when withdrawn, so a distribution can create a tax bill as well as reduce the contract value.
For example, a surrender charge typically equals 7 percent of the amount withdrawn in the first year of the contract. That charge applies under contract terms, separately from any tax penalty. A financial advisor can help you compare withdrawal timing with other retirement income strategies before you take money from a deferred annuity.
Surrender Periods and Withdrawal Access
A surrender period is the contract window when withdrawals beyond a permitted amount can incur surrender charges. For annuities such as fixed indexed annuities, these periods can range from three to 10 years. Many deferred annuities allow penalty-free withdrawals of up to 10% of contract value, but the specific contract determines the available amount and applicable conditions.
Taking more than the allowed amount during that period may trigger a charge, and a market value adjustment may apply to excess partial withdrawals or a full surrender. These terms affect how much money remains available for unexpected needs. Before choosing a contract, consider how guaranteed income plans fit your expected cash needs during the surrender period. A financial advisor can help assess that fit.
Fixed indexed annuity growth and principal protection
For people considering protecting retirement assets with fixed indexed annuities, the central tradeoff is potential index-linked interest without direct investment in the index. The crediting formula, withdrawal rules, and other contract terms determine how that protection works.
Unlike a variable annuity, a fixed indexed annuity doesn’t directly invest in the stock market or its linked index. Some contracts won’t credit less than 0% interest when the index falls, but that floor applies to interest credits, not every possible reduction in contract value. Withdrawals, surrender charges, and other contract terms can still affect the amount available. Guarantees depend on the issuing insurance company’s financial strength and claims-paying ability.
There isn’t one cap, participation rate, or spread that applies to every contract. For example, a 7% cap limits credited growth to 7% even if the index rises more; an 80% participation rate applied to a 10% index gain credits 8%, before any cap. A 3% spread applied to an 8% index return leaves 5% credited interest.
To choose and purchase an annuity, compare its index formula, floor, surrender terms, and riders with your income needs and access to principal. Ask the agent how the cap, participation rate, and spread affect interest credits, when terms can change, and what happens after withdrawals. If your goal is protecting retirement assets with fixed indexed annuities, also consider how the insurer’s financial strength supports its guarantees.
These details can help you determine whether an annuity could serve as one part of a retirement income stream, rather than replace every variable or liquid asset. Review the contract’s federal tax treatment and surrender provisions before committing funds.
Safe Harbor Financial Resources: Medicare Supplement Insurance (Medigap)
Safe Harbor Financial Resources offers Medicare Supplement Insurance (Medigap) for people considering how healthcare coverage fits into retirement plans. Fixed indexed annuities address contract-based growth and income, while Medigap is a separate coverage consideration. Keeping these needs distinct can help you evaluate retirement resources alongside Medicare coverage.
If you’re reviewing retirement priorities, Safe Harbor Financial Resources can also discuss life insurance options, including Life Insurance with Living Benefits, Term Life Insurance, and Whole Life Insurance. The right conversation depends on the need you’re addressing: potential retirement income, healthcare coverage, or financial protection for loved ones. Understanding each option’s purpose can help you make a clearer plan without treating one product as a substitute for another.
Contact Safe Harbor Financial Resources to discuss Medicare Supplement Insurance and how it fits your priorities.
Set a Clear Course for Your Retirement Plan
Decide what you want your retirement plan to support: dependable income, access to savings, healthcare needs, or support for loved ones. Write down your priorities and outstanding questions. That gives you a clearer starting point for considering whether protecting retirement assets with fixed indexed annuities fits alongside your broader financial decisions.
Safe Harbor Financial Resources offers Medicare Supplement Insurance (Medigap), Life Insurance with Living Benefits, and Term Life Insurance. These options address different needs, so a focused conversation can help you explore what’s most relevant to your plans without treating one solution as a substitute for another.
Contact Safe Harbor Financial Resources to discuss your priorities and take your next step with greater clarity.
Frequently Asked Questions
Are Annuities Insured?
Annuities aren’t FDIC-insured bank deposits. Contractual guarantees depend on the issuing insurance company’s ability to meet its claims. Consider the insurer’s financial strength separately from the annuity’s index-crediting formula and payout design. This distinction matters if you’re relying on future contract payments as part of your retirement income plan.
Questions about annuities?
Ask how interest credits are calculated, which withdrawals are available, when surrender charges apply, and how optional riders affect the contract. Also consider how the annuity fits with your other retirement income sources and savings goals. For people in Palm Beach Gardens, discussing these questions with a financial advisor can clarify how contract terms relate to individual plans.
What are the Risks of an Annuity?
Key risks include limited access to money during surrender periods, reduced purchasing power if inflation outpaces growth, and reliance on the issuing insurer’s claims-paying ability. Annuities can also limit growth compared with direct investment because index-linked credits follow contract formulas. Before committing funds, consider whether you’ll need that money for emergencies or near-term expenses.
When is a solution like this appropriate?
A fixed indexed annuity may suit someone assigning a portion of long-term savings to contract-based growth or future income while keeping other assets available for nearer-term needs. For example, a retiree whose essential expenses are covered by other income might consider whether an annuity aligns with longer-range goals. It may be less suitable for money needed soon or for someone seeking direct market investment.
How do fixed indexed annuities protect retirement savings from market losses?
Fixed indexed annuities don’t directly invest in the linked index, so a decline in that index doesn’t automatically create a matching contract loss. Instead, the contract applies its interest-crediting formula, which may credit no interest for a period when the index falls. That protection has limits: withdrawals and contract terms can still affect the value available to you.
Comments