


Whole Life with Living Benefits: 2026 Florida Guide
What if your life insurance didn't just wait for the end of the journey, but acted as a sturdy anchor you could lean on while you're still enjoying the Florida sunshine? Most families in Palm Beach Gardens worry that a sudden health crisis or the rising costs of assisted living, which now average over $70,000 annually in our state, could wash away their hard-earned retirement savings. It's natural to feel anxious about market volatility or the complex jargon that makes financial planning feel like a storm you can't steer through alone.
We're here to help you find calm. This guide shows you how whole life insurance with living benefits serves as a protective refuge, providing a liquid emergency fund and a shield against the financial impact of chronic illness. You'll discover how the 2026 tax-advantaged limits, including the $430 daily IRS per-diem for chronic illness, work together to secure your family's legacy while supporting your needs today.
Beyond the Death Benefit: Why Whole Life Insurance is Now a Living Asset
Traditional thinking often paints life insurance as a gift for the future, but modern Whole life insurance has evolved into a "dual-purpose anchor" for your financial ship. Choosing whole life insurance with living benefits means you aren't just securing a legacy; you're building a refuge you can use during your own lifetime. If a health storm hits, these provisions allow you to accelerate a portion of the death benefit to cover immediate needs. It's a vital shift from a "just-in-case" expense to an active, living asset that provides calm and stability in the face of uncertainty.
The Role of Guaranteed Cash Value as a Living Resource
As you pay your premiums, your policy builds a guaranteed cash value that grows steadily with tax advantages. This isn't like a traditional retirement account that locks your money behind a wall of age restrictions or heavy withdrawal penalties. Instead, it serves as a reliable reservoir for life's unexpected turns. Many Florida families find peace of mind knowing they have a financial cushion that isn't tied to the volatile swings of the stock market.
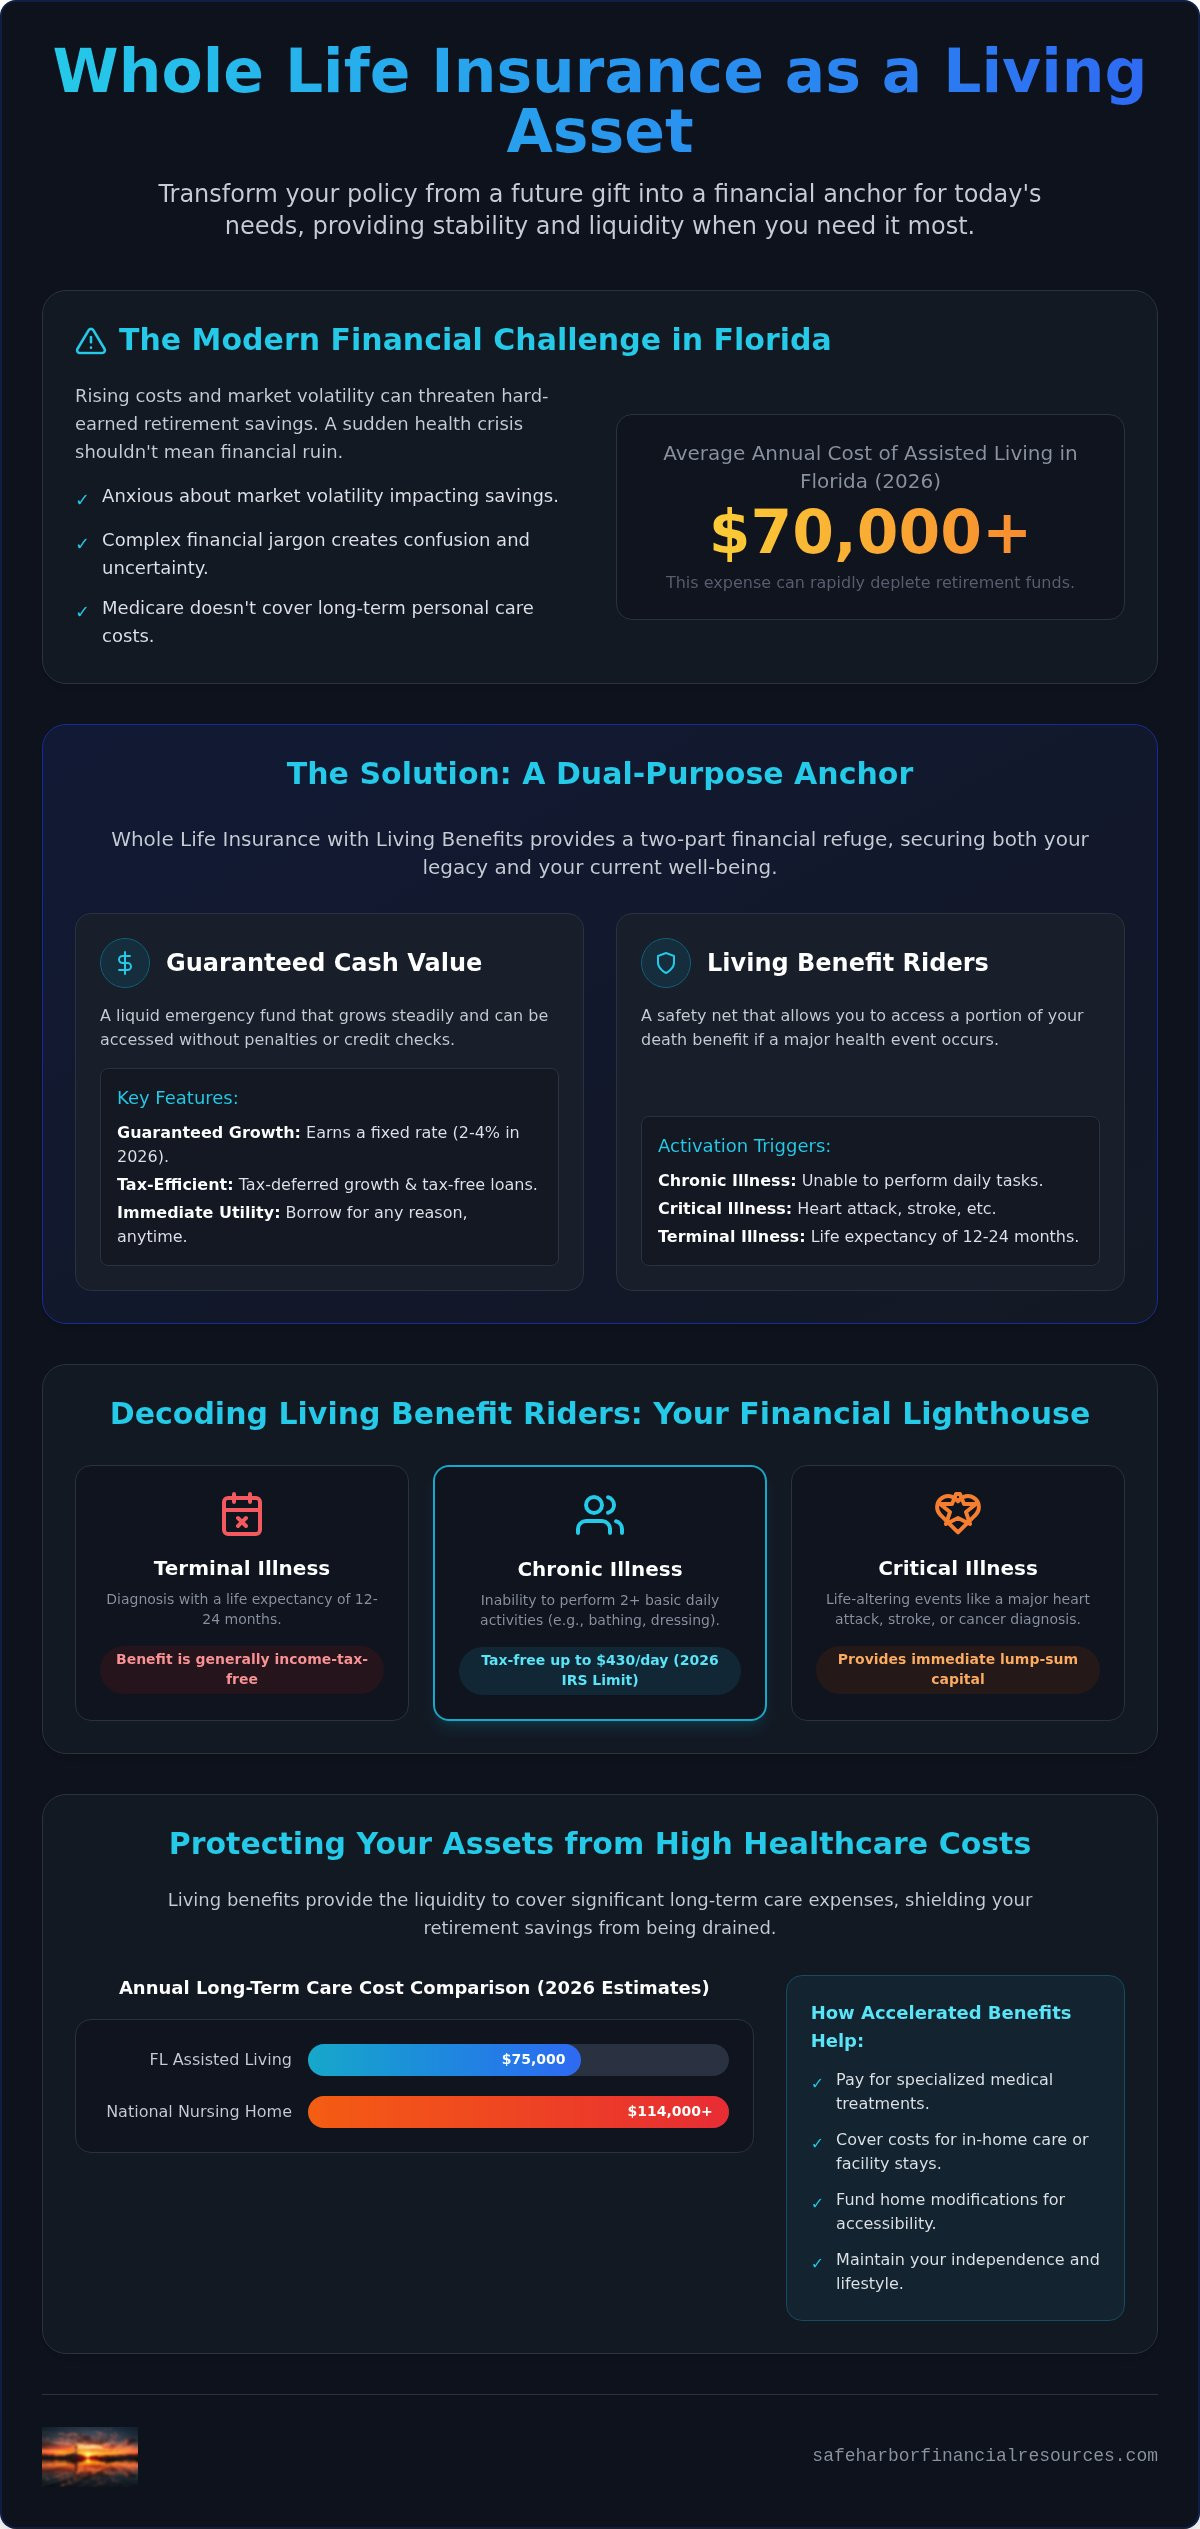
Guaranteed Growth: Your cash value typically earns a fixed interest rate between 2% and 4% as of 2026.
Immediate Utility: You can borrow against the value for any reason, whether it's for home repairs or supplementing income.
Tax Efficiency: Growth is tax-deferred, and loans are generally received income-tax-free.
Cash value is a liquid emergency fund that requires no credit check to access, providing you with immediate capital whenever you need a steady hand. By treating your policy as a living resource, you ensure that your financial foundation remains firm, regardless of what the horizon holds.
Decoding Living Benefit Riders: Critical, Chronic, and Terminal Illness Protection
Understanding how whole life insurance with living benefits works requires looking at the specific "triggers" that unlock your policy's value while you're still active. These typically include terminal, chronic, and critical illnesses. A terminal diagnosis involves a life expectancy of 12 to 24 months, while chronic illness triggers when you can no longer perform basic daily tasks like bathing or dressing. Critical illness riders cover sudden, life-altering events such as a stroke or heart attack. Think of these riders as a lighthouse in a storm. They provide a clear signal and a way forward, ensuring your family's finances don't crash against the rocks of unexpected medical debt. While these features might slightly adjust your premium, the security they offer acts as a vital safety net.
How Accelerated Death Benefit Riders (ADBR) Function
When you activate an ADBR, you essentially "accelerate" a portion of your death benefit to use now. It's vital to remember that receiving these funds reduces the final payout to your heirs, but the immediate utility is often worth the trade. The flexibility is remarkable; you can use this capital for anything from specialized treatments to home modifications. For instance, with the national median cost for a nursing home room exceeding $114,000 in 2026, having this liquidity can save your retirement savings from being drained.
Florida residents also benefit from favorable tax treatment. Living benefit payouts for terminal illness are generally income-tax-free, and chronic illness benefits are typically excludable up to the 2026 IRS per-diem limit of $430. You can explore various living benefit options to find the right fit for your specific needs. Since riders vary by carrier, it's wise to consult a Safe Harbor professional to see which protections are currently available for your family.
Securing Your Palm Beach Retirement: The Safe Harbor Approach to Permanent Coverage
Seniors in Palm Beach Gardens face unique financial currents that require a steady hand. With Florida assisted living costs averaging between $70,000 and $75,000 annually in 2026, relying solely on basic savings can feel like sailing without a compass. This is why many neighbors are turning to whole life insurance with living benefits. While Medicare Supplement plans handle hospital stays and doctor visits, they don't address the long-term personal care that often accompanies aging. By layering permanent coverage with your health plan, you create a comprehensive refuge that protects your legacy and your lifestyle.
This strategy allows you to use the living benefits of life insurance to bridge the gap between medical insurance and actual living expenses. It's about more than just numbers; it's about maintaining your independence. You can learn more about how to protect assets from nursing home costs in Florida to ensure your home and savings remain within your family's reach, even if your health needs change.
Integrating Life Insurance into a Comprehensive Florida Financial Plan
Local expertise is the rudder that keeps your plan on course. Managing Florida's regulatory landscape for accelerated death benefits requires precision, as riders vary significantly by carrier. We believe your financial milestones should be celebrations of a well-protected life rather than sources of stress. Whether you're entering retirement or reviewing an existing portfolio, your plan deserves a steady guide who understands the local environment.
A rigorous inquiry into your current coverage can reveal if gaps exist that a health crisis might exploit. By reviewing your whole life insurance with living benefits alongside your other assets, we can help you find the calm and stability you deserve. Reach out to our team at Safe Harbor for a personal assessment of your unique situation and to ensure your financial ship is built for the long haul.
Charting Your Course Toward Lasting Financial Peace
Your retirement years should be a time of celebration, not a period defined by financial anxiety. By choosing whole life insurance with living benefits, you're securing a permanent anchor that provides both a guaranteed legacy and a liquid resource for your health needs. These modern policies offer a refuge against the rising costs of care in Florida, ensuring your savings remain intact even during life's challenging storms.
Safe Harbor Financial Resources provides expert guidance on Florida-specific Medicare and life insurance through local, face-to-face consultations. As an independent brokerage, we offer the personalized, maritime-strength protection your family deserves. We invite you to request a complimentary professional assessment of your living benefits today. Let's work together to ensure your financial ship is prepared for the horizon ahead. You've earned the right to feel secure in your future.
Frequently Asked Questions
What is the main difference between whole life insurance and living benefits?
Whole life insurance is the permanent policy that serves as your long-term financial anchor, while living benefits are specific riders that allow you to access your death benefit early. Think of whole life as the ship and living benefits as the specialized gear that protects you during a storm. While the policy provides a guaranteed legacy, these riders ensure you have a refuge if your health changes.
Can I use living benefits to pay for non-medical expenses?
Yes, you can use these funds for any purpose once the benefit is triggered. While many Florida families use the capital for specialized medical care, you're free to use it for home modifications, daily bills, or even family travel. Having whole life insurance with living benefits provides the flexibility to navigate life's transitions without the stress of rigid spending restrictions on your own assets.
How much of my death benefit can I access while I am still alive?
The amount you can accelerate depends on your specific policy and the severity of your condition. Many riders allow you to access 50% to 90% of the death benefit for terminal illness. For chronic conditions, payouts often follow the 2026 IRS per-diem limit of $430 for tax-advantaged benefits. Since these riders vary by carrier, it's vital to review your specific contract with a steady guide.
What happens if I have a living benefit rider but never get sick?
If you never need to use your living benefits, your policy continues to function as a traditional shield for your heirs. The full death benefit, minus any cash value loans, will be paid to your beneficiaries tax-free. This is why whole life insurance with living benefits is so reassuring. It provides a safety net if you need it, but preserves your legacy if you stay healthy.


Comments