


Guide to Medicare Parts A, B, C & D in Palm Beach Gardens
What if your 65th birthday was less of a paperwork headache and more of a celebration of the security you’ve worked so hard to build? Many of our neighbors in Palm Beach Gardens feel a genuine sense of dread when those thick Medicare envelopes start arriving, especially with the looming uncertainty of rising healthcare costs in 2026. It’s easy to feel lost in the fog of late-enrollment penalties and the confusing differences between Part C and Medigap.
You deserve to feel like you’re entering a safe harbor rather than drifting at sea. We’ll help you master the nuances of Medicare Parts A B C and D so you can protect your retirement assets from medical debt. This guide provides a clear mental map of each essential part. We’ll show you how to anchor your coverage with confidence, ensuring your plan is perfectly optimized for our local Florida provider networks.
The Foundation of Your Security: Medicare Parts A and B (Original Medicare)
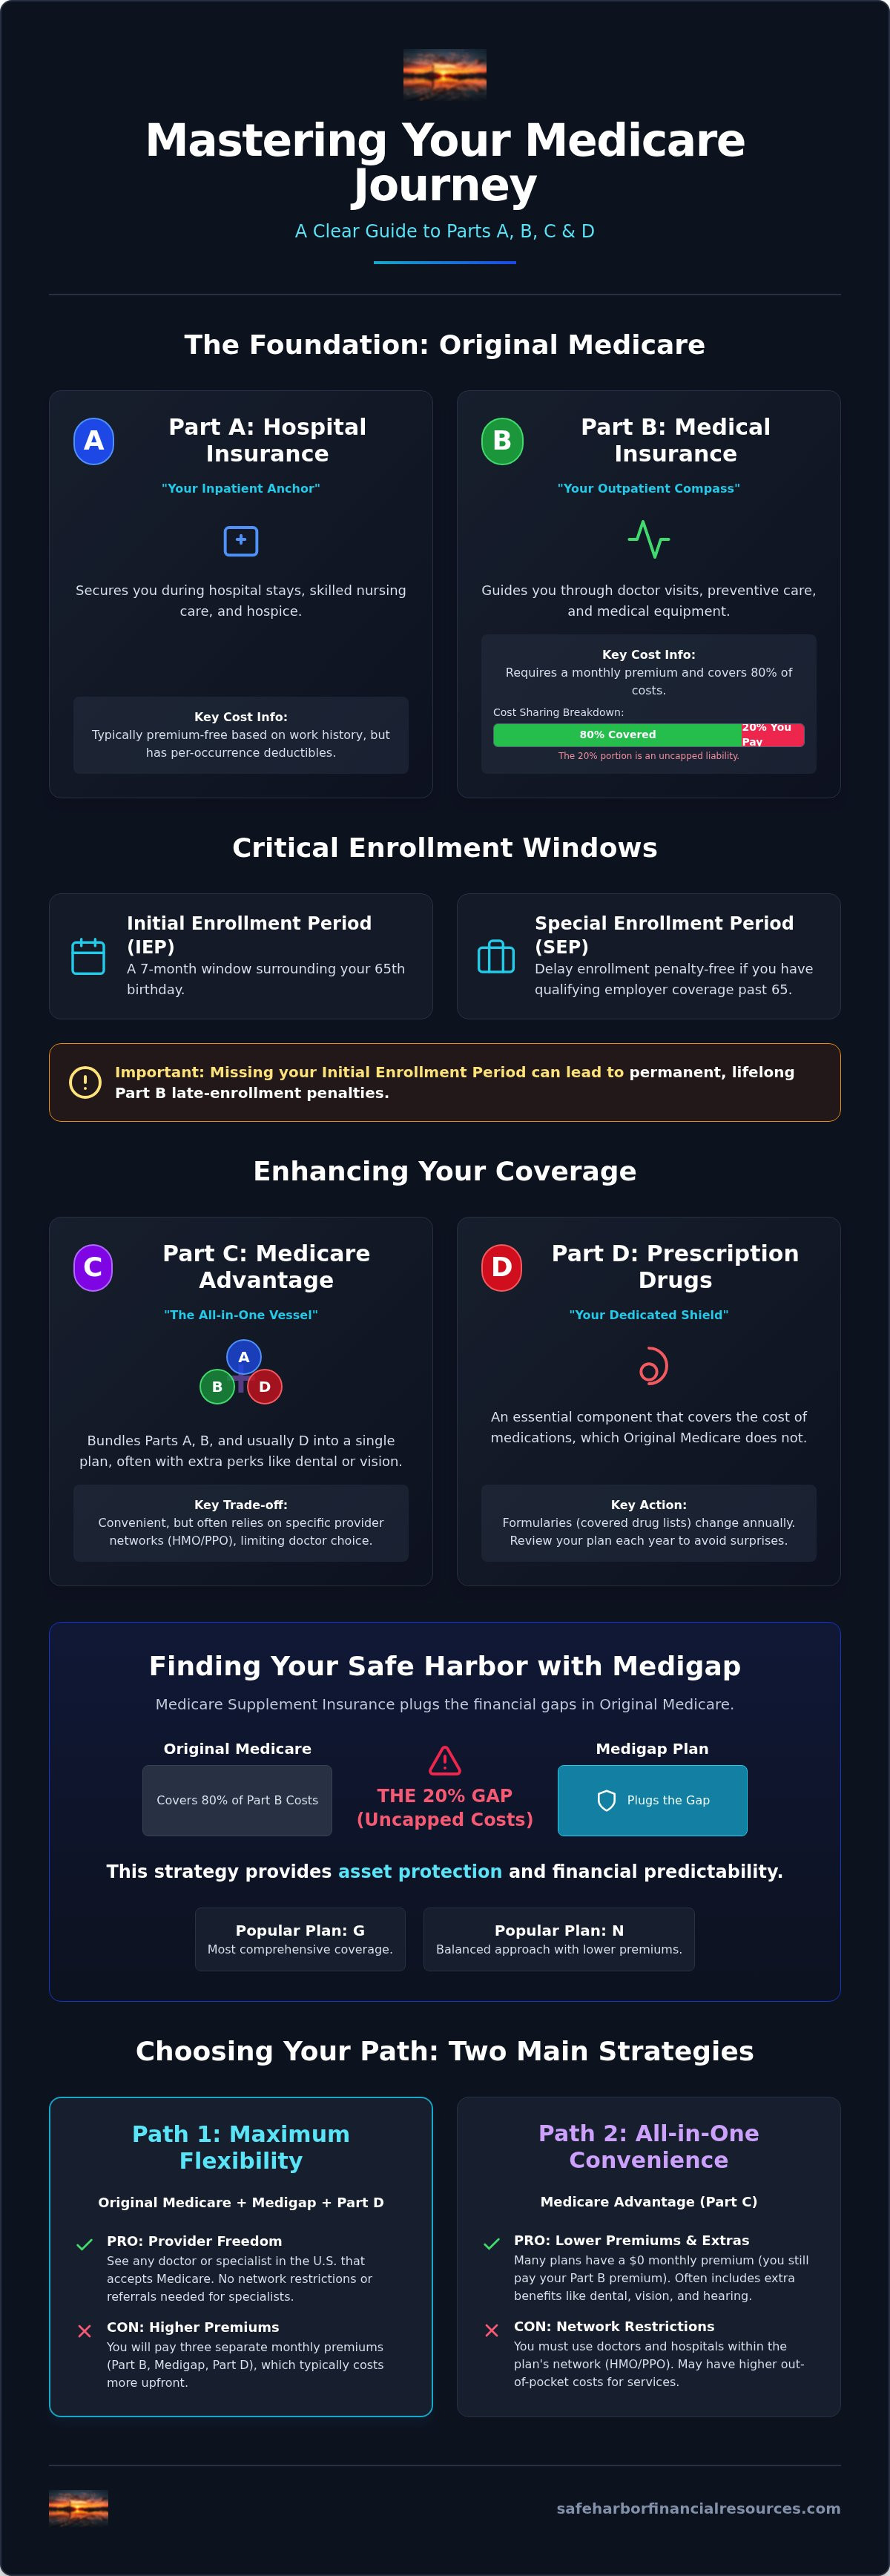
Understanding the core of Medicare Parts A B C and D begins with the two pillars of Original Medicare. Think of Part A as your inpatient anchor. It secures you during hospital stays, skilled nursing care, and hospice. Most residents in Palm Beach Gardens qualify for premium-free Part A based on their work history; however, the per-occurrence deductibles can still leave your retirement assets vulnerable if you're hospitalized multiple times a year. This part provides the base of your protection, but it isn't designed to cover everything.
Part B acts as your outpatient compass. It guides you through doctor visits, preventive screenings, and durable medical equipment. This part requires a monthly premium and generally covers 80% of approved costs. That remaining 20% is an uncapped liability that can grow quickly without additional coverage. As we look toward 2026, staying informed about CMS updates is vital. While exact premiums are pending official release, preparing for potential adjustments ensures your financial harbor remains steady and your access to local specialists isn't compromised.
Enrollment Timelines for Palm Beach Gardens Residents
Timing is everything. Your Initial Enrollment Period is a seven-month window centered around your 65th birthday. Missing this deadline can lead to lifelong Part B penalties that increase your monthly costs forever. Local residents often coordinate with Social Security offices in Palm Beach County to verify their status and ensure their transition is celebratory rather than stressful. If you continue to work past 65 with qualifying employer coverage, a Special Enrollment Period allows you to delay enrollment without facing those permanent late fees once your employment ends.
Enhancing Your Coverage: Medicare Parts C and D
Once you've secured your foundation with Original Medicare, you can choose how to enhance your protection. Medicare Part C, often called Medicare Advantage, acts as an all-in-one vessel. It bundles the benefits of Parts A and B into a single plan, usually including Part D prescription coverage and extra perks like dental or vision. Evaluating the full scope of Medicare Parts A B C and D allows you to decide if a bundled approach or a modular one fits your lifestyle best. While this convenience is appealing, it's vital to understand the trade-offs. Advantage plans often rely on specific provider networks, whereas Original Medicare paired with a Medicare Supplement Insurance (Medigap) plan offers the flexibility to see any doctor who accepts Medicare.
Medicare Part D serves as a dedicated shield against the rising costs of medications. Since Original Medicare doesn't cover most prescriptions, Part D is an essential component of a complete strategy for Medicare Parts A B C and D. Choosing the right plan ensures you aren't blindsided by out-of-pocket expenses at the pharmacy. This protection is especially critical as drug pricing structures evolve, making a well-chosen plan a vital anchor for your retirement budget.
Choosing Between Advantage and Prescription Drug Plans
In Palm Beach Gardens, your choice often depends on your relationship with your doctors. If you prefer Part C, you must verify that your local specialists are in-network. Florida HMO and PPO networks can change, so a plan that fits today might require a shift tomorrow. For those who value consistency, checking your local plan options with a professional can provide the clarity you need to stay with the providers you trust.
Your Part D plan also requires an annual "check-up." Formularies, which are the lists of covered drugs, change every year. A medication covered this year might move to a higher cost tier or be dropped entirely next year. Reviewing your coverage annually protects your retirement assets from unexpected pharmacy bills and ensures your medications remain affordable.
Navigating Your Choices: Finding Your Safe Harbor with Medigap
While the standard components of Medicare Parts A B C and D provide a solid base, Original Medicare has a notable "leak" in the form of the 20% coinsurance you're responsible for. Medicare Supplement Insurance, or Medigap, acts as a secondary hull to your ship. It covers those gaps, ensuring that a single major health event doesn't capsize your financial security. For many Florida seniors, Plan G and Plan N have become the preferred choices. Plan G offers the most comprehensive coverage for those who want total predictability; Plan N provides a balanced approach with slightly lower premiums in exchange for small copays at certain doctor visits.
This strategic combination is about more than just paying doctor bills. It’s about asset protection. By securing a Medigap plan, you prevent unexpected hospital or skilled nursing costs from depleting the retirement savings you spent decades building. It transforms your healthcare strategy into a reliable anchor, giving you the freedom to enjoy your retirement without the anxiety of uncapped medical debt. Choosing this path provides a level of stability that allows you to focus on your health rather than your bank balance.
Why a Local Palm Beach Gardens Professional is Your Best Ally
Finding your way through the local insurance market requires more than just a brochure. You need a protective mentor who understands how Florida providers interact with specific plans. We specialize in helping you build a personalized 2026 Medicare roadmap through a complimentary assessment, ensuring your coverage is as precise as it is protective. To stay informed about local health resources and community updates, you can connect with Dennis Richards on Facebook. Let’s work together to ensure your healthcare journey remains a celebratory milestone rather than a source of stress.
Steer Your Retirement Toward a Secure Horizon
Medicare shouldn't feel like a storm you have to weather alone. By understanding the specific roles of Medicare Parts A B C and D, you've already taken the first step toward anchoring your future. You now know that while Original Medicare provides the base, local network choices and strategic supplements like Medigap are what truly shield your assets from rising costs. As licensed Medicare Supplement experts, we provide independent agency transparency and personalized Palm Beach County guidance to ensure your plan is as resilient as it is reliable.
Don't let the complexity of 2026 keep you from the peace of mind you deserve. You're invited to Secure Your Peace of Mind with a Professional Medicare Assessment today. We're here to help you turn this milestone into a celebration of your long-term security. Your future is bright, and with the right guide, your healthcare coverage will be too.
Frequently Asked Questions
Is Medicare Part A completely free for everyone?
Medicare Part A is premium-free for most Palm Beach Gardens residents who have paid Medicare taxes for at least 10 years. If you don't meet this work history requirement, you may have to pay a monthly premium. Even with premium-free Part A, you're still responsible for deductibles and coinsurance for hospital stays, which is why understanding the full scope of Medicare Parts A B C and D is vital for your security.
What is the main difference between Medicare Part C and a Medigap plan?
The main difference is how they interact with Original Medicare. Medicare Part C (Advantage) replaces your Original Medicare with a private plan that often includes drug coverage and network restrictions. In contrast, a Medigap plan works alongside your Original Medicare to pay the "gaps" like your 20% coinsurance. Choosing between these options is a key step in mastering Medicare Parts A B C and D to protect your retirement assets.
Can I have both a Medicare Advantage plan and a Medigap policy at the same time?
You cannot legally have both a Medicare Advantage plan and a Medigap policy at the same time. These two paths are mutually exclusive ways to enhance your healthcare coverage. If you currently have an Advantage plan and want to switch to a Medigap policy, you'll typically need to leave the Advantage plan first. A local Palm Beach County guide can help you navigate this transition during the appropriate enrollment periods.
How much does Medicare Part B cost in 2026?
Official premiums and deductibles for Medicare Part B in 2026 haven't been released yet by the Centers for Medicare and Medicaid Services (CMS). These figures are typically announced late in the preceding year. We encourage our Palm Beach Gardens neighbors to stay alert for these updates. We can help you adjust your retirement roadmap once the specific costs are confirmed to ensure your financial harbor remains secure.


Comments