


Retirement Income Planning in 2026: Building Your Safe Harbor
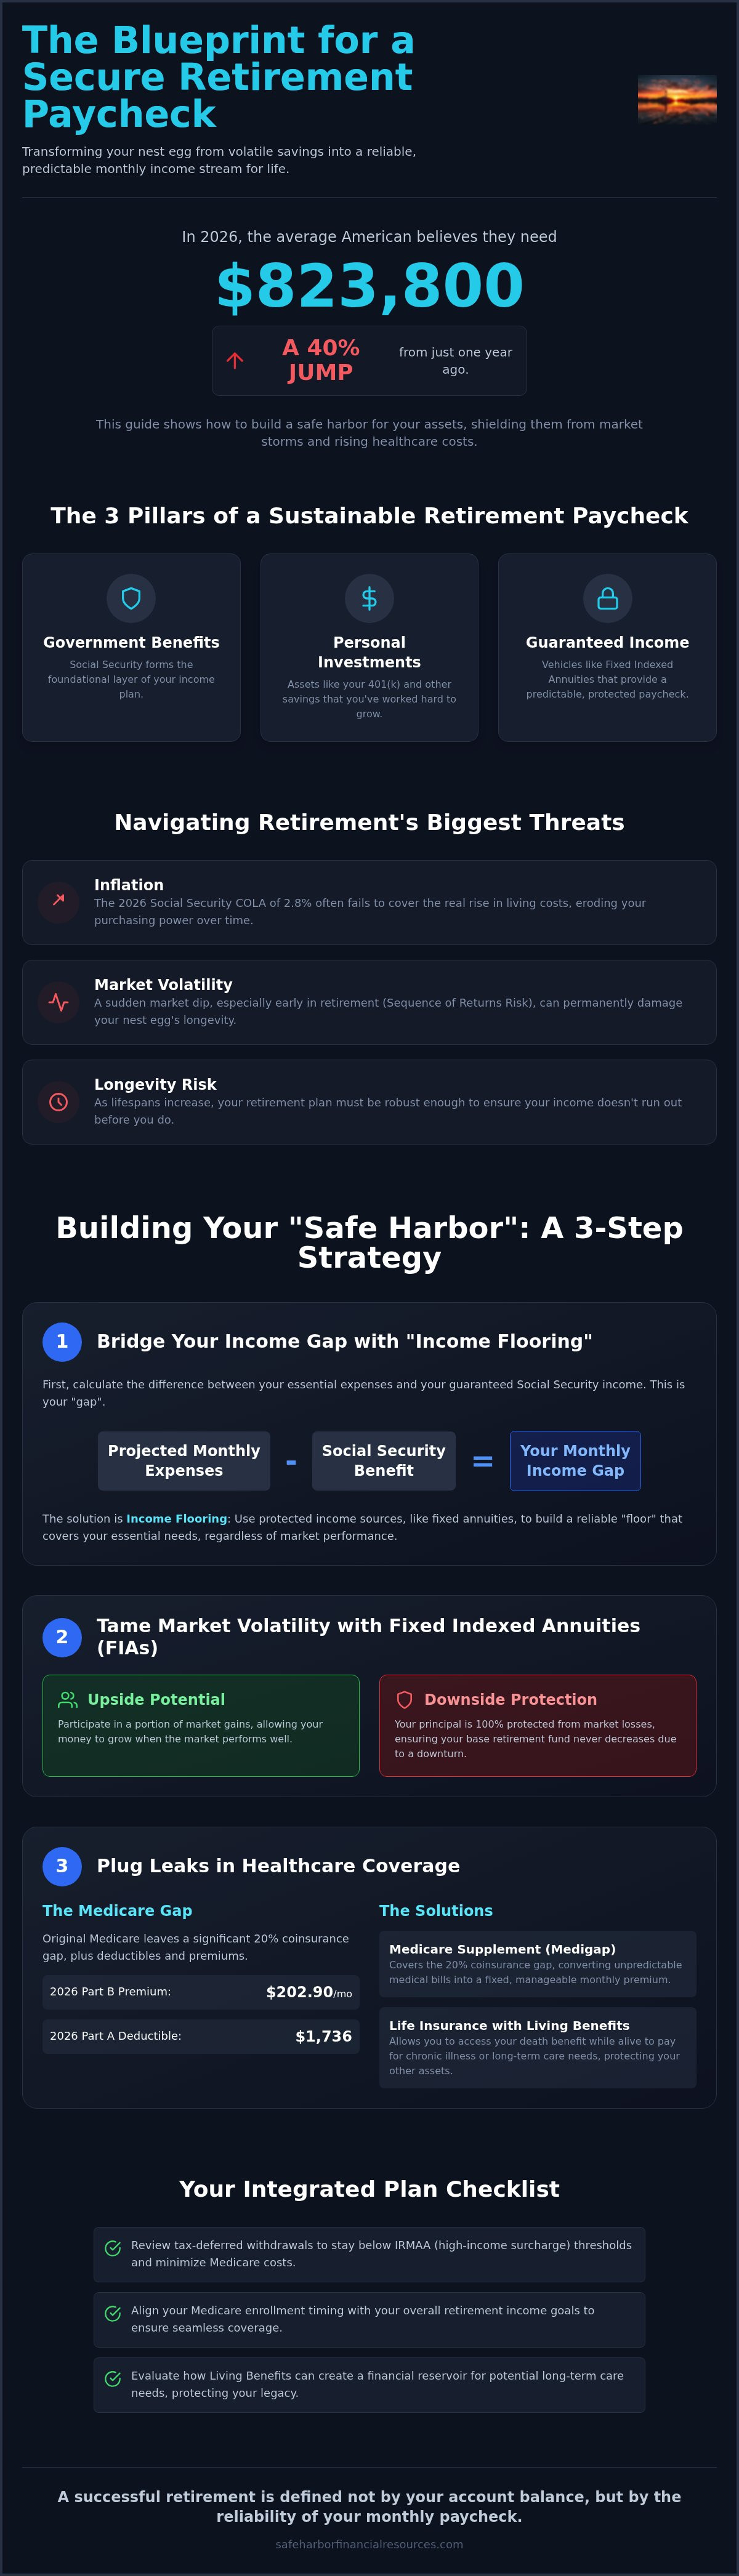
In 2026, the average American believes they need $823,800 to retire comfortably, a staggering 40% jump from just one year ago. It's natural to feel a sense of weight when you look at your 401(k) and wonder if it can withstand market storms or the rising costs of healthcare in Florida. You've worked hard to build your nest egg. The fear of a market dip eroding your life's work is a heavy burden to carry.
This guide will show you how to master retirement income planning to transform those volatile savings into a predictable monthly paycheck that stays steady even when the economy doesn't. We'll explore how to shield your assets from long-term care costs and bridge the gaps in Medicare. You'll learn to build a safe harbor that protects your legacy and ensures your peace of mind remains anchored.
The Pillars of a Sustainable Retirement Paycheck
Effective Retirement planning involves more than just saving; it's the strategic coordination of Social Security, personal nest eggs, and private insurance. In 2026, the traditional "three-legged stool" has evolved. It now rests on government benefits, personal investments like a 401(k), and guaranteed income vehicles such as fixed indexed annuities.
This structure defends against the primary threats to your security:
Inflation: The 2026 Social Security COLA of 2.8% helps, but it rarely covers the rising costs of a Florida lifestyle.
Market Volatility: Sudden market dips shouldn't force you to sell assets at a loss to pay your bills.
Longevity Risk: As we live longer, your retirement income planning must ensure your money doesn't run out before you do.
To better understand how these pillars fit together, watch this helpful guide:
Bridging the Gap Between Social Security and Your Lifestyle
Calculating your "income gap" is a vital exercise for every retiree. Start with your projected monthly expenses in Palm Beach Gardens, then subtract your expected Social Security benefit. The remaining number is your gap. We solve this through "Income Flooring." This strategy ensures essential needs, like housing and healthcare, are covered by guaranteed sources. By using tools like fixed annuities, you create a baseline of security that doesn't fluctuate with the stock market. This holistic approach to retirement income planning ensures your legacy is preserved while you live your best life today.
Protecting Your Income Harbor from Market Volatility
The greatest fear many retirees face is a market crash occurring just as they step away from the workforce. This is known as sequence of returns risk. If the market dips early in your journey, you might be forced to withdraw from a shrinking pot, which can permanently damage your nest egg's longevity. While traditional stock and bond portfolios offer growth, they often lack the sturdy anchor needed for secure retirement income planning during economic gales.
A resilient strategy focuses on stability. As you prepare for retirement, you need to identify which assets are exposed to the open sea and which are safely docked. Diversification is helpful, but it doesn't eliminate downside risk. True retirement income planning requires a dedicated portion of your wealth to remain untouched by market downturns, ensuring your monthly paycheck never falters.
The Role of Fixed Indexed Annuities in a Stable Plan
Fixed Indexed Annuities (FIAs) serve as a powerful tool for those seeking both growth and protection. These vehicles allow you to participate in a portion of market gains while ensuring your principal remains entirely safe from market losses. It's the best of both worlds. For Florida residents, the tax-deferred growth of an FIA helps maximize your savings over time, keeping more of your money working for you rather than the IRS. This approach transforms anxiety into certainty. If you're ready to see how an FIA can strengthen your specific "Safe Harbor" strategy, a personal consultation can provide the clarity you need. Reach out through our Facebook page to start the conversation.
Managing Healthcare Costs and Long-Term Security
Healthcare expenses represent the largest potential leak in your financial hull. For many seniors, medical costs can drain hundreds of thousands of dollars over a lifetime. In Palm Beach County, a Medicare Supplement (Medigap) plan is essential for predictable budgeting. It covers the 20% coinsurance that Original Medicare leaves behind. By securing a Medigap policy, you turn unpredictable medical bills into a manageable monthly premium. This allows your retirement income planning to stay on course without sudden shocks from hospital stays or specialist visits.
Reliable Retirement planning information highlights that Medicare doesn't cover everything. For instance, in 2026, the Medicare Part B standard monthly premium is $202.90, and the Part A deductible has reached $1,736. These figures show why a proactive approach is necessary. Life Insurance with Living Benefits offers a versatile solution. It protects your family if you pass away, but it also provides funds if you face a chronic illness, acting as a secondary anchor for your security.
Integrating Medicare and Living Benefits into Your Strategy
Coordinating your healthcare and income requires precision. To avoid high-income surcharges, known as IRMAA, you must time your withdrawals carefully. Follow this simple checklist to keep your plan steady:
Review your tax-deferred withdrawals to stay below IRMAA thresholds.
Align your Medicare enrollment with your retirement income planning goals.
Evaluate how Living Benefits can act as a reservoir for long-term care needs.
Living Benefits allow you to access your death benefit while you're still alive to pay for care. This ensures you don't have to drain your savings to stay afloat. Learn more about How to Protect Assets from Nursing Home Costs in Florida to keep your legacy intact for your heirs.
Charting Your Course to a Secure Future
You've worked hard to build your savings; now it's time to ensure they work just as hard for you. A successful retirement isn't just about the balance in your bank account. It's about the reliability of the monthly paycheck you receive. By coordinating Social Security with protected vehicles like fixed indexed annuities and securing your health with Medigap, you create a shield against the unexpected. Effective retirement income planning turns your anxiety into a celebration of your life's achievements.
Our licensed professionals in Palm Beach Gardens are dedicated to your peace of mind. We provide personalized Medicare and annuity strategies that act as a steady guide in this landscape. Take the first step toward your protected future today. Request Your Complimentary Retirement Income Assessment and let us help you anchor your legacy. Your safe harbor is within reach.
Frequently Asked Questions
What is the best age to start retirement income planning?
The ideal time to begin is at least 10 years before you plan to stop working. This window, often called the retirement red zone, gives you enough time to shift from accumulation to preservation. Starting early ensures your retirement income planning accounts for market shifts and allows you to lock in protection strategies before health changes occur.
How much of my income should come from guaranteed sources versus market investments?
Most experts recommend covering your essential expenses with guaranteed sources. This includes your housing, utilities, and food. By using Social Security and fixed annuities to create an income floor, you ensure your basic needs are met regardless of stock market performance. Your market-based investments can then be used for lifestyle spending, such as travel or hobbies, which can be adjusted if the market dips.
Will Medicare cover all my healthcare costs in retirement?
Original Medicare does not cover everything. You are typically responsible for 20% of outpatient costs and various deductibles. In 2026, the Part A deductible is $1,736 per benefit period. To avoid these leaks in your budget, many Florida seniors choose a Medicare Supplement plan to provide predictable, fixed monthly costs for their medical care and peace of mind.
What are the tax advantages of retirement planning for Florida residents?
Florida is a tax-friendly harbor because it has no state income tax. This means your Social Security benefits and retirement account withdrawals aren't taxed at the state level. Additionally, using tools like fixed indexed annuities allows your interest to grow tax-deferred. This combination helps you keep a larger portion of your hard-earned savings for your own lifestyle and your heirs.
How do Fixed Indexed Annuities differ from traditional savings accounts?
While a savings account offers liquidity and a low fixed rate, a Fixed Indexed Annuity is designed for long-term retirement income planning. FIAs provide the potential for higher interest credits linked to a market index, but with a guarantee that you'll never lose principal due to market downturns. They act as a protective shell for your legacy rather than a simple cash reserve.


Comments