


Annuity Payout Options: Anchoring Your Retirement Income in 2026
What if the greatest risk to your Palm Beach Gardens retirement isn't a market crash, but a simple misunderstanding of your annuity payout options? You've spent decades building a nest egg. It's natural to feel a sense of dread when faced with technical terms like "Period Certain" or "Joint and Survivor." The fear of outliving your savings is a heavy burden, especially as inflation threatens your future purchasing power. We believe these major life transitions should be celebrated, not feared.
This guide will clarify the distribution landscape for 2026, helping you transform your accumulated savings into a reliable, monthly anchor. You'll discover how to protect your surviving spouse, manage RMDs at age 73 or 75, and ensure your income remains steady regardless of market shifts. We'll break down complex payout structures into clear, actionable steps so you can move forward with absolute confidence and the peace of mind you deserve.
Understanding Annuity Payout Options: Finding Your Financial Safe Harbor
Transitioning from the accumulation phase to the distribution phase is a celebratory milestone for Palm Beach Gardens retirees. It represents the moment your years of hard work transform into a reliable stream of income. Annuitization effectively turns your contract value into a guaranteed monthly check, acting as a steady anchor for your Florida lifestyle. By locking in a payout, you replace market anxiety with the calm of a predictable budget.
Choosing the right path requires clarity because these decisions are often permanent. Understanding Annuity Payout Options is vital for long-term security, as each choice involves specific trade-offs between current cash flow and future protection. We view this process as charting a course through a complex landscape, ensuring your financial vessel remains stable regardless of shifting economic tides.
To better understand how these choices affect your monthly income, watch this helpful video:
The "Life Only" Option: Maximum Income vs. Legacy Risk
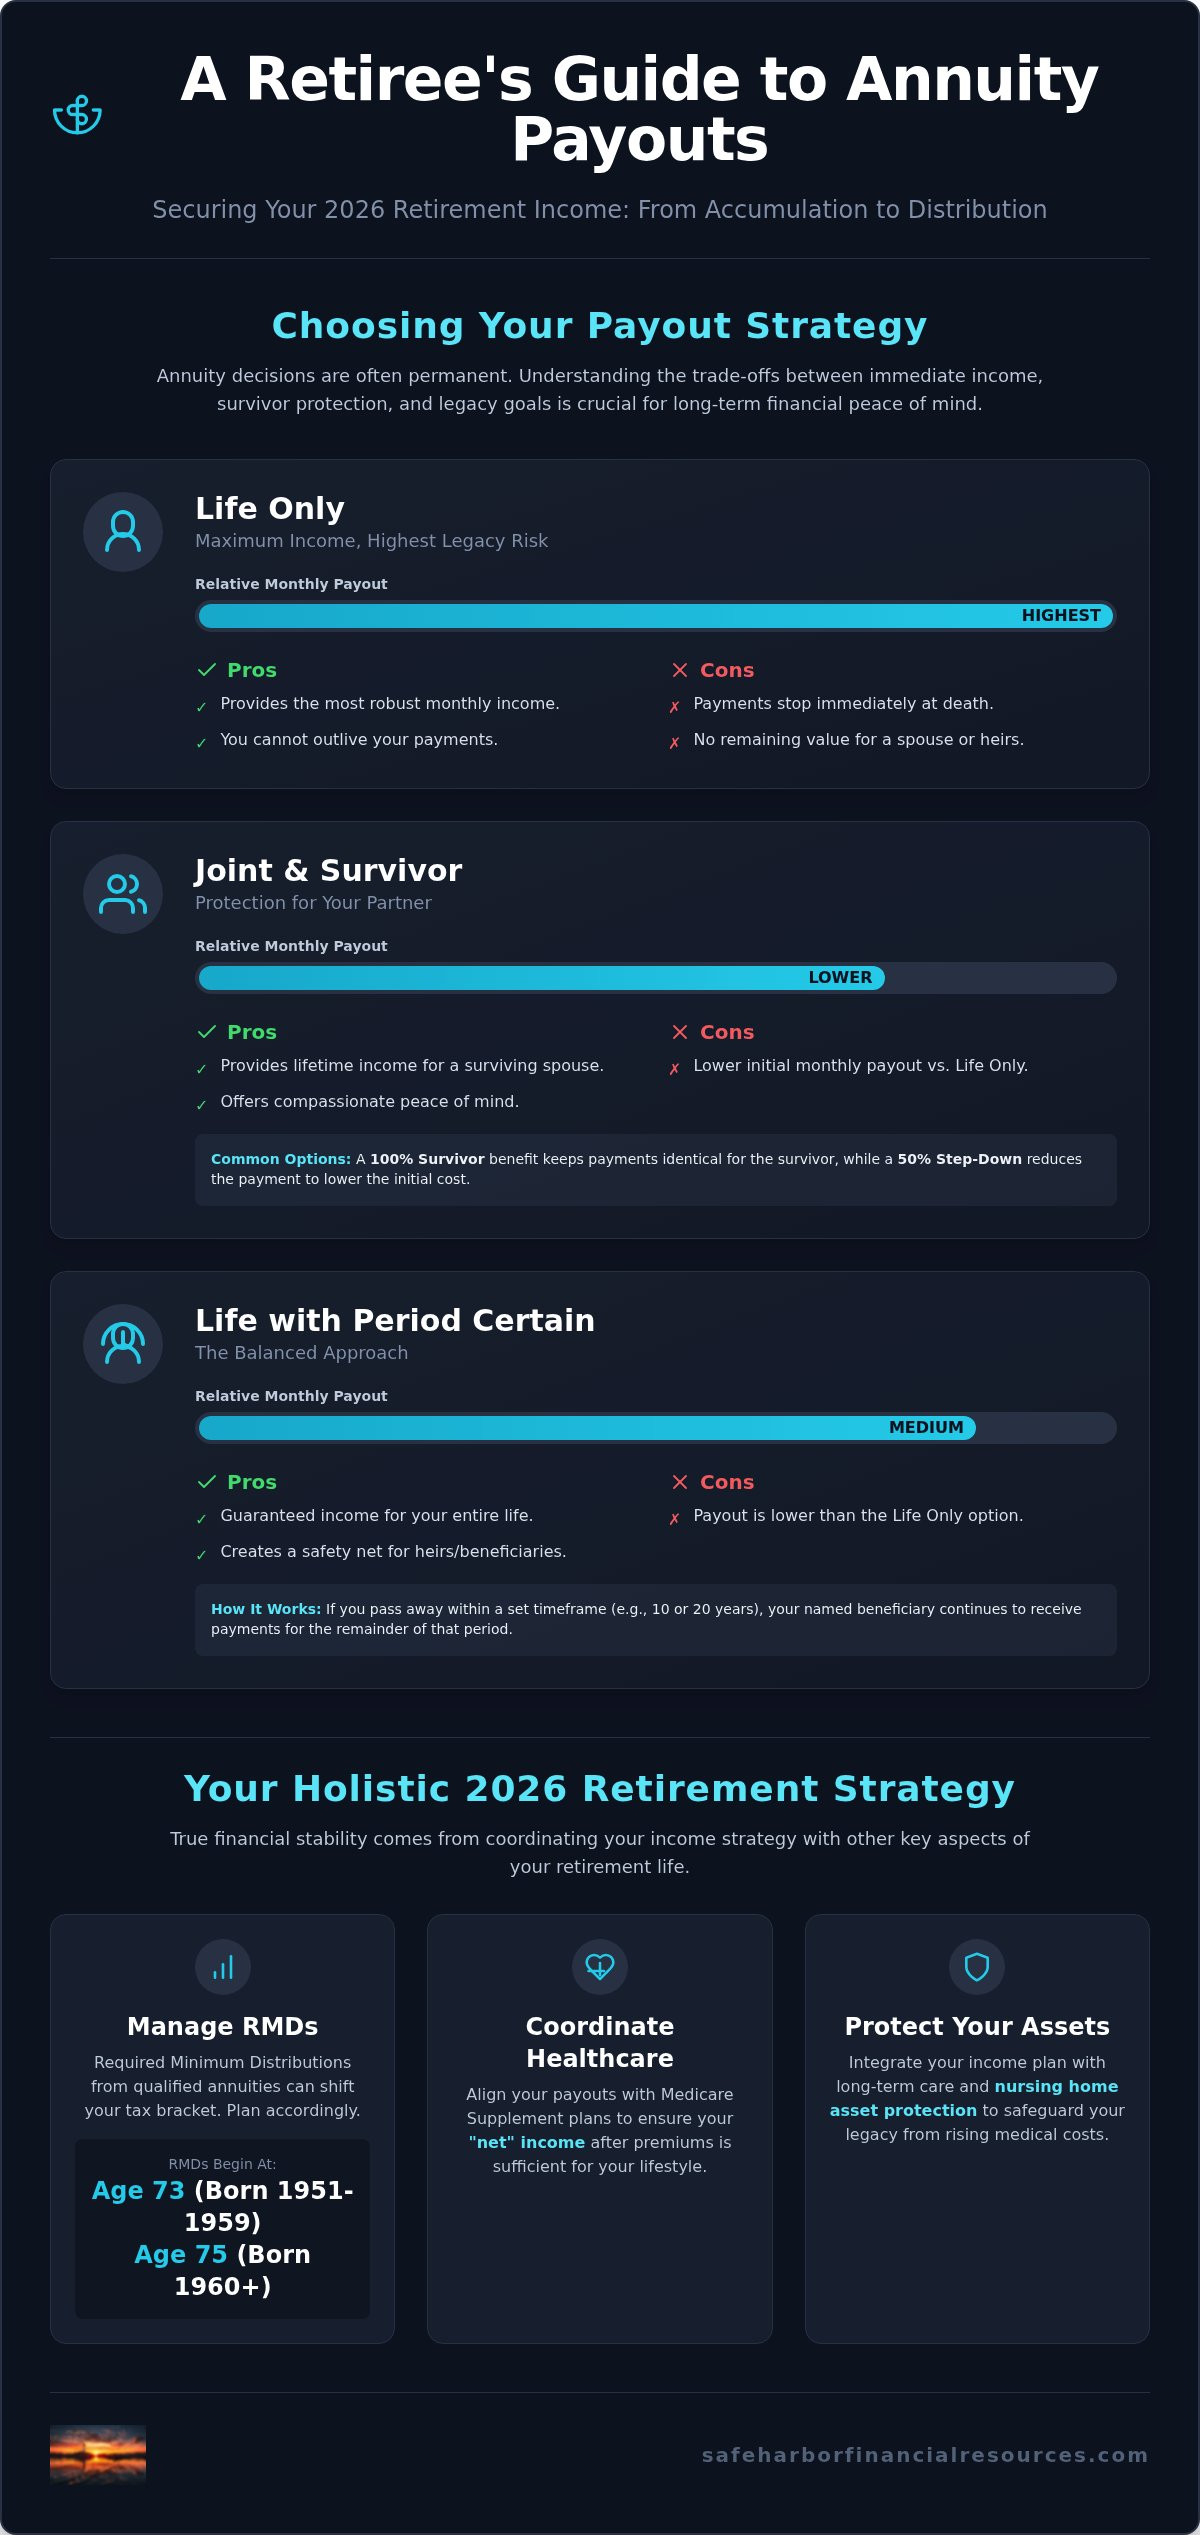
The Life Only choice typically offers the highest monthly check available. This happens because the insurance company assumes the risk of your longevity without the obligation of continuing payments to others. While the higher income is attractive for covering daily expenses, it creates a potential "survivor gap." If you pass away early, the payments stop immediately, which might leave a spouse vulnerable without a coordinated strategy. Life Only is essentially a wager on your own longevity that provides the greatest immediate cash flow.
Highest immediate payout: Provides the most robust monthly income for active retirees.
Longevity protection: You can't outlive the payments, no matter how long you live.
Legacy trade-off: There's no remaining value for heirs or a surviving spouse once the annuitant passes.
Comparing Payout Strategies: Which Anchor Is Right for You?
Selecting the right path for your income requires looking beyond your own needs. Choosing the right annuity payout options provides a sense of calm, ensuring that your spouse is never left without a financial refuge, regardless of who lives longer. This choice acts as a protective shield for your household, preventing the income from vanishing if one partner passes away. While the monthly check might be slightly lower than a single-life option, the long-term security it offers for a surviving spouse is often the most compassionate choice for a shared retirement.
When Evaluating Your 2026 Retirement Strategy, you might find that Life with Period Certain offers the ideal middle ground. This strategy provides a guaranteed monthly check for your entire life, but also names a beneficiary who will receive payments if you pass away within a set timeframe, such as 10 or 20 years. It acts as a safety net, ensuring that your hard-earned savings don't simply stay with the insurance company if your journey is cut short unexpectedly.
Joint and Survivor vs. Period Certain: A Legacy Comparison
Florida couples often weigh a 100% survivor benefit against a 50% step-down option. A 100% benefit keeps the payment identical for the survivor, whereas a step-down reduces the check to lower costs today. If you're concerned about heirs, "Period Certain" guarantees that your estate receives value even if you pass away shortly after selecting your annuity payout options. For a personal look at how these choices impact your Palm Beach County future, visit our Safe Harbor Facebook page.
You may also consider lump sum distributions or systematic withdrawals. These offer more flexibility but lack the lifetime guarantees of true annuitization. Without that guaranteed anchor, you face the risk of outliving your funds if the market turns or your needs increase. Choosing a structured payout replaces that uncertainty with a seal of quality and long-term security.
Evaluating Your 2026 Retirement Strategy in Palm Beach Gardens
Your retirement income doesn't exist in a vacuum. To find true stability, you must coordinate your annuity payout options with your Medicare Supplement plans. This alignment ensures your "net" income, the cash actually landing in your pocket after healthcare premiums, is sufficient to maintain your Florida lifestyle. By treating these two pillars as a single protective shield, you create a more reliable financial refuge for the years ahead.
Tax efficiency is another vital part of your 2026 strategy. If you hold a qualified annuity, remember that Required Minimum Distributions (RMDs) now begin at age 73 for those born between 1951 and 1959, or age 75 for those born in 1960 or later. These mandatory distributions can shift your tax bracket unexpectedly. Consulting this Investor.gov guide to annuities helps you understand how different distribution methods might affect your bottom line.
True peace of mind also means looking toward potential long-term care needs. Integrating your annuity payout options with nursing home asset protection provides a more holistic safety net. This approach safeguards your hard-earned legacy from being eroded by rising medical costs, ensuring your income anchor remains firm during life's more challenging transitions.
Five Steps to Selecting Your Payout Option
Choosing your path should be a celebration of your hard work, not a source of stress. Follow these five steps to secure your future:
Step 1: Calculate your "Floor" by listing essential monthly expenses like housing, utilities, and groceries.
Step 2: Assess your health and family history to estimate your potential longevity needs.
Step 3: Determine the specific income requirements of your surviving spouse or beneficiaries to prevent a survivor gap.
Step 4: Analyze the tax impact of your chosen distribution method on your 2026 tax bracket.
Step 5: Consult with a local Palm Beach Gardens expert to model different scenarios tailored to your unique goals.
Securing Your Financial Safe Harbor for the Years Ahead
Your retirement journey in 2026 should be a time of celebration, not a period of uncertainty. By carefully selecting the right annuity payout options, you transform your hard-earned savings into a steady anchor for your Florida lifestyle. Whether you prioritize the maximum income of a Life Only plan or the protective refuge of a Joint and Survivor strategy, your decision provides the stability you deserve. Coordinating these distributions with your healthcare costs ensures your financial vessel remains balanced.
We're here to serve as your steady guide. Our team provides trusted local guidance in Palm Beach Gardens, focusing on Fixed Indexed Annuities and seamless Medicare integration. Request a Personalized Retirement Income Review today to secure your financial safe harbor. You've worked hard for this milestone; it's time to enjoy the peace of mind that comes with a well-charted course.
Frequently Asked Questions
What is the most popular annuity payout option for Florida couples?
Joint and Survivor Life is the most common choice for Florida couples. It ensures income continues as long as either spouse is alive, providing a sense of calm for Palm Beach Gardens households. It eliminates the "survivor gap" where a spouse might lose essential income upon the first partner's death. This protective strategy is a cornerstone of shared retirement stability.
Can I change my annuity payout option after payments have started?
Generally, no; once you annuitize your contract and payments begin, the decision is permanent. This is why evaluating your annuity payout options with precision is so vital before you sign. Some modern contracts offer limited liquidity features or "commutation" rights, but these are rare. Most retirees should view their selection as a lifelong commitment to a specific, guaranteed income structure.
How do annuity payout options affect my Required Minimum Distributions (RMDs)?
Annuitizing a qualified annuity satisfies your RMD requirements for that specific account. In 2026, those born between 1951 and 1959 must start RMDs at age 73; those born in 1960 or later wait until age 75. The periodic payments are considered your distribution, simplifying your tax obligations and providing a steady, predictable income anchor for your household.
Will my annuity payout increase with inflation in 2026?
Standard fixed payouts remain level, but you can choose options with a Cost-of-Living Adjustment (COLA). While a COLA helps protect your purchasing power in Palm Beach Gardens, it typically starts with a lower initial monthly check. Some Fixed Indexed Annuities also offer "increasing income" riders that adjust based on index performance, offering a potential refuge when comparing annuity payout options.


Comments